
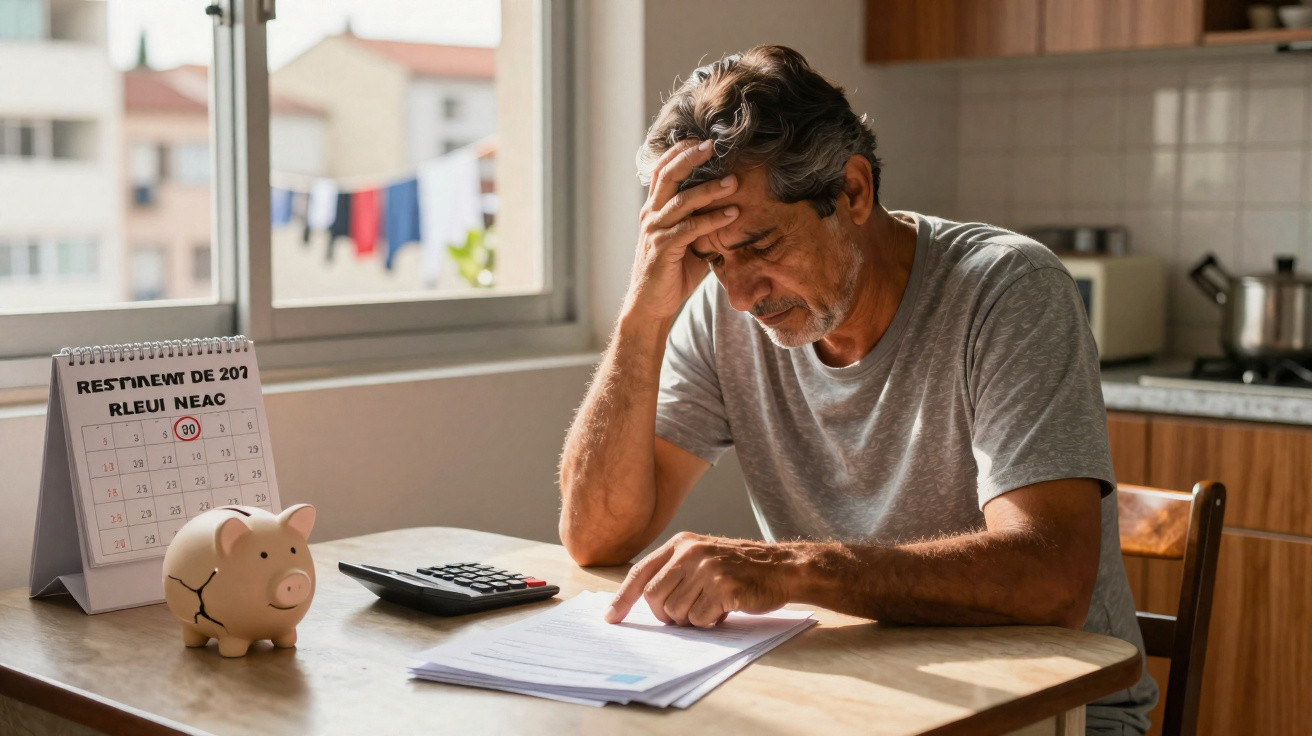
Years pass. Income limits move by a few pounds. Rules on working hours are adjusted. For thousands of people in the middle of their careers, seemingly minor alterations can remove the financial support they expected to rely on during the final years of work.
Mark was sitting under the kitchen light, the only lamp still on, when he opened the letter. For three evenings, he had stayed up late trying to make a spreadsheet work when it had never been designed to hold so much pressure. His plan had appeared straightforward: reach 55, draw a modest lump sum, reduce his shifts, carry on funding the children’s sport and keep up the mortgage payments. The letter then told him that the minimum age for access was rising. On paper, two years may not seem significant. In someone’s life, it can change everything. He read again the sentence explaining that the support would no longer apply. He studied his hands as a mechanic might after a lengthy shift. We have all experienced that feeling when the rules change after we have already paid to take part. The envelope rustled as he filed it away. Quietly, something else had shifted as well.
Where the new boundaries fall - and who bears the cost
The pattern becomes clear on closer inspection: eligibility ages have increased, income limits have risen more slowly than wages, and the hours needed to receive employer contributions have become stricter. Taken separately, these adjustments can look administrative. Combined, they reshape who receives support later in their working life. People who based their plans on access at 55 must now wait until 57. Middle earners who previously received tax relief or credits may find themselves just above the limit after a pay rise that scarcely kept pace with inflation. The details vary across sectors and schemes, with different abbreviations and terminology. Yet the result is remarkably similar.
Consider Angela, a supervisor whose shift pattern changes unpredictably. Her employer introduced a “minimum hours per quarter” requirement to qualify for the full employer contribution. It appears fair in principle. In reality, a fortnight off sick and an altered rota left her 8 hours below the requirement. She receives no employer contribution this quarter. Across a year, that creates a four-figure shortfall. She does not become angry; she works through the numbers again. A survey by a major benefits platform indicates that thousands lose out by margins that seem trivial in theory but harsh in a household budget. A spreadsheet has no regard for how nearly someone qualified.
There are several reasons behind these changes. Governments are dealing with ageing populations and growing long-term commitments. Employers are under pressure from rising costs and changing regulations. Adjusting limits attracts less attention than announcing outright cuts, and it is easier to do quietly. Indexation that lags behind real living costs, fresh caps that exclude those who are almost eligible, and age criteria based on actuarial models rather than lived circumstances all play a part. The underlying message is clear: work slightly longer, earn a little more and qualify later. The problem is that the disorder of real life does not fit policy calculations. Miss a week of work or receive a small pay rise, and the support can disappear.
What to do as retirement thresholds move
First, list every threshold that affects you: access-age rules, income bands for tax relief or credits, and minimum working hours for employer contributions. Then test your plan against two modest disruptions: losing one shift each month and receiving a small pay increase that takes you above a limit. Create a “Plan B” that can absorb both possibilities. For some people, this will mean putting a little more into an emergency fund to cover the years before access becomes available. For others, it could involve seeking more regular hours or distributing overtime differently to avoid falling over an income cliff edge.
After that, monitor your eligibility as routinely as you monitor your daily steps. A brief check each month is more effective than a frantic annual review. Save screenshots of online account pages. Maintain a one-page record of the conditions that make you eligible and those that disqualify you. Ask HR to confirm employer contribution rules in writing, including whether missed hours can be carried forward. Realistically, hardly anyone will do this every day. Even so, one habit matters above all the others: put rule-reset dates in your calendar. Eligibility often changes at quarter ends or with the start of a tax year. Spot those periods in time, and you may retain money that would otherwise be lost.
Thresholds sound impersonal until their impact is described by the people affected. “It felt like the rules had changed overnight” is a sentiment heard in many settings, from nurses and delivery drivers to middle managers. Narrow differences determine who receives assistance and who goes without it. The answer is not simply for individuals to work harder. It also requires transparency and pressure for fairer rules.
“We didn’t expect a big payout. We just planned around the rules we were given. Then the age moved, and the match slipped, and the tax break vanished because I worked two extra Sundays.”
- Know the cliff edges: Find the precise income and hours limits at which support falls to zero.
- Ask about exceptions: sick leave, caring responsibilities and union arrangements may allow exemptions if you raise the issue.
- Automate the routine tasks: Create reminders for quarter-end hours totals and tax-year income thresholds.
- Build up “gap year” cash: even a modest reserve can cover a missed employer contribution or delayed access.
- Keep records of everything: Emails, policy documents and payslips create the evidence trail needed to win disputes.
The wider issue behind the figures
These changes involve more than calculations; they affect something vulnerable: trust. People organise their lives around stated boundaries, even when they have never examined the small print. When those boundaries move, planning starts to feel like aiming at a moving target. Some will respond through better tactics, additional jobs or postponed retirement dates. Others will reduce their ambitions. Many will trade stories around kitchen tables about limits that shifted by inches but damaged a year by miles. There is no neat resolution. There is only the decision to share the information available, demand rules that reflect real lives and help one another identify the blind spots created when the small print starts to bite.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Age and access changed | Early-access ages have increased in several systems, postponing lump sums and phased retirement | Helps you plan cash flow and avoid being forced into gap years |
| Income and hours cliff edges | New bands and minimum-hour requirements disqualify workers by very narrow margins | Identifies where a small adjustment can restore lost money |
| Documentation makes a difference | Written confirmation and clear records can often overturn incorrect refusals | Offers a practical way to challenge decisions and recover benefits |
FAQ:
- What has changed in “retirement thresholds”? The principal changes concern access ages, income bands for tax relief or credits, and the minimum hours required for employer contributions. The adjustments may be small, but their consequences can be substantial.
- Why did I lose a benefit after a modest pay rise? You may have crossed a cliff edge where eligibility ends immediately rather than reducing gradually. Being £1 above the limit can mean receiving no benefit.
- Can I challenge a missed employer contribution? In some cases, yes. If the shortfall resulted from sick leave, rota mistakes or payroll errors, written evidence may secure an exception or a corrective contribution.
- How can I protect my plan if the access age increases? Set aside a “gap fund” for the additional months, reduce hours gradually instead of retiring completely, and investigate whether partial payments are still available.
- What should I ask HR or my provider now? Request the current limits, reset dates, exceptions policy and the method used to inform members about rule changes. Obtain the answers in writing.
Comments
No comments yet. Be the first to comment!
Leave a Comment