
I realised my money was controlling me, rather than the other way round, while standing in my kitchen and looking at three near-identical coffee machines. One sat on the worktop, another was in the cupboard ‘just in case’, and a third remained unopened from a flash sale I could scarcely remember clicking on.
My banking app had just sent its usual red alert - one I had trained myself to treat as background noise. I was not buying yachts; I was buying takeaways, attractive storage baskets and ‘small treats’ that somehow consumed my pay packet.
That morning, amid cardboard boxes and uncomfortable silence, I realised I was reliving the same thing.
I did not need yet another budget. I needed to identify the loop I was trapped in.
The hidden loop behind overspending
The shift happened when I quit asking, “Where did my money go?” and began asking, “When do I lose control?”
Not what. Not how much. When.
As soon as I focused on the timing, a pattern began to emerge, like a watermark on a banknote. My most reckless spending always followed the same sort of day: lengthy, exhausting days filled with minor frustrations that accumulated like unwashed dishes. I would arrive home worn out, pick up my phone to ‘relax’, and suddenly have a basket containing £87 of things I had not even wanted that morning.
It was not random spending. It was a ritual.
One Monday evening made it undeniable. Work had been difficult: last-minute alterations, a meeting that ought to have been an email, and an unclear remark from my manager that weighed on my chest like a stone. I walked home replaying the day, feeling diminished and oddly empty.
By the time I got to the sofa, my mind wanted only one thing: escape. Twenty minutes later, I was deep in an online shop, putting candles, skincare and a velvet cushion promising “hotel-style comfort” into my basket. The total came to £126.
The following day, I reviewed my banking history from the previous month. There had been ten similar evenings. Ten similar totals. The same times, the same apps and the same feelings. The products changed, but the emotional receipt did not.
When I plotted it all out, the explanation was painfully obvious. I was not spending for pleasure; I was spending to soothe myself.
My repeating pattern was ‘emotional overtime’: whenever I swallowed irritation, insecurity or fatigue during the day, the invoice appeared that evening as checkout confirmations. Money was simply the instrument I used to purchase an illusion of control.
That one pattern explained much more than my old colour-coded budget ever had. Figures alone had not helped because they cannot reason with emotion. Patterns do.
As soon as I gave it a name, the spell weakened slightly.
The 10-Minute Delay habit that broke the spending spell
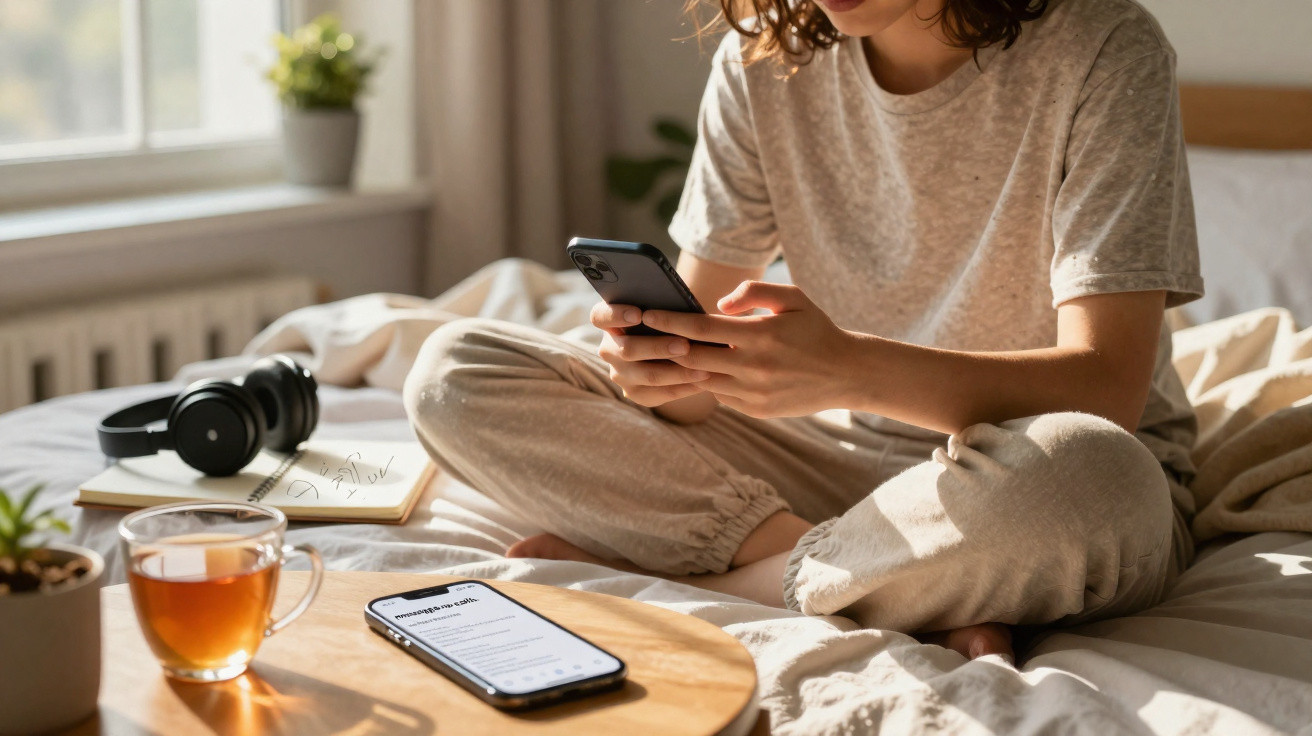
I did not begin with an elaborate system. I began with a two-line note in my phone called ‘The 10-Minute Delay’.
The rule was straightforward: every non-essential purchase above £20 had to wait ten minutes. In those ten minutes, I had to record three details: what I wanted to purchase, the time, and how I felt. Nothing more. No calculations or criticism - simply a pause long enough to catch myself doing it.
On most evenings, my notes read something like: “9:47pm – body scrub – tired / flat / annoyed”. Sometimes I still pressed ‘buy’. Yet on other occasions, those ten minutes were enough to interrupt the trance.
For years, my mistake had been leaping straight into drastic fixes. No-spend months. Strict budgets. Complicated tracking apps that I gave up after four days. Let’s be honest: nobody really does this every single day.
The 10-minute delay seemed minor, even slightly ridiculous, which was precisely why I followed it. I was not forbidding purchases; I was disrupting a pattern. That made me feel less defensive and more inquisitive.
If you have ever deleted your banking app from shame or avoided checking your balance until payday, you will recognise that dense, lingering feeling. This small habit was not intended to create perfection. It was meant to create lightness: just enough distance between emotion and purchasing to ask, “What’s really going on here?”
Over several weeks, the ongoing record in my phone became a mirror. I did not enjoy everything it reflected, but at last I understood it.
“Money doesn’t just show what we value. It shows what we’re trying to avoid feeling.”
The notes began revealing recurring themes, so I turned them into a simple boxed list I could scan quickly:
- Spending trigger: late-night scrolling after bad workdays
- Spending style: small, ‘harmless’ comfort buys that add up
- Real need: rest, reassurance, and a sense of achievement
- Cheap alternative: call a friend, 10-minute walk, hot shower, quick journal
- Red-flag time: anything after 9:30pm on weekdays
Seeing it set out this way made it seem less like a personal failing and more like a pattern I could gradually rewire.
What changes when you see the pattern
Once my recurring money pattern was obvious, practical adjustments felt unexpectedly simple. I made myself a deliberately silly rule: “No emotional purchases after 9:30pm.” I removed my card details from my favourite shopping sites and left my phone in the kitchen overnight. Rather than relying on willpower, I changed the setting where the offence took place.
Something else changed as well. Earlier in the week, I began arranging small, genuine treats: coffee with a friend midweek, a solo cinema visit, or a better lunch on Wednesday rather than a panic delivery on Thursday. The more authentic comfort I included in my days, the less I searched for artificial comfort in flash sales.
What surprised me most was not the money I saved, although that increased month after month. It was how much quieter my mind became. The steady buzz of guilt faded. I no longer woke with that persistent sense of “What did I do last night?” about my spending.
The simple reality is: most overspending is not about failing to know better; it is about failing to notice sooner. When you can identify a pattern and say, “Oh, there you are”, you create a small but powerful space between impulse and action. In that space, wiser decisions suddenly become possible, without feeling like punishment.
And then you realise you never hated money. You hated feeling out of control.
Your repeating pattern may be entirely different. Perhaps it is payday euphoria, when your account is full and you feel entitled to everything you have been denying yourself. Perhaps it is social pressure: the quiet anxiety of splitting a bill with friends whose earnings differ from yours. Or perhaps it is sale season, when ‘saving 40%’ somehow results in spending 60% more than intended.
Whatever yours is, identifying it is the real financial upgrade. One identified pattern beats ten unused budgets.
When you look back over the past three months of spending, what keeps returning? A time of day, an emotion, a place, a person, an app? That is the thread worth pulling. Not all at once - only enough to see what begins to unravel.
| Key point | Detail | Value for the reader |
|---|---|---|
| Notice the ‘when’, not only the ‘what’ | For a few weeks, record the time, mood and context of every non-essential purchase | Reveals your individual money loop instead of blaming your willpower |
| Build a simple pause ritual | Use a 10-minute delay and a brief note before purchasing anything above a chosen amount | Gives your mind room to move from emotional to intentional spending |
| Plan around trigger moments | Adjust your environment and arrange small, healthy rewards in advance | Helps better money choices feel natural rather than restrictive or punitive |
FAQ:
Question 1 How can I identify my own repeating money pattern when my spending seems chaotic?
Begin with only two weeks of gentle tracking. Without judging yourself, note the time, location and mood behind every non-essential purchase. Then look for repeated elements: the same hour, app or feeling. That is usually where the pattern is hiding.Question 2 What if my pattern is “I spend whenever I’m bored”?
Boredom is a trigger too. Make a list of three fast, free alternatives, such as a walk, a podcast or a 15-minute declutter, and place it on your lock screen. The aim is not to stop spending forever, but to offer your mind another route when boredom arrives.Question 3 Can I use this if I already have debt and feel behind?
Yes. Recognising your pattern does not replace addressing debt, but it can stop you silently adding to it. It is like repairing a leak before trying to bail out the water. Even small successes here can make debt plans feel far more manageable.Question 4 Do I need an expensive app to track my spending triggers?
No. A messy notebook or a basic notes app can work equally well. The power lies not in the tool, but in the pause and the awareness. One line for each purchase is sufficient.Question 5 What if I recognise the pattern but still overspend sometimes?
You are human, not a spreadsheet. Change is untidy and inconsistent. The aim is not never to slip up; it is to do so less often, with greater awareness and less shame. Every time you spot the pattern a little earlier, that is progress.
Comments
No comments yet. Be the first to comment!
Leave a Comment