
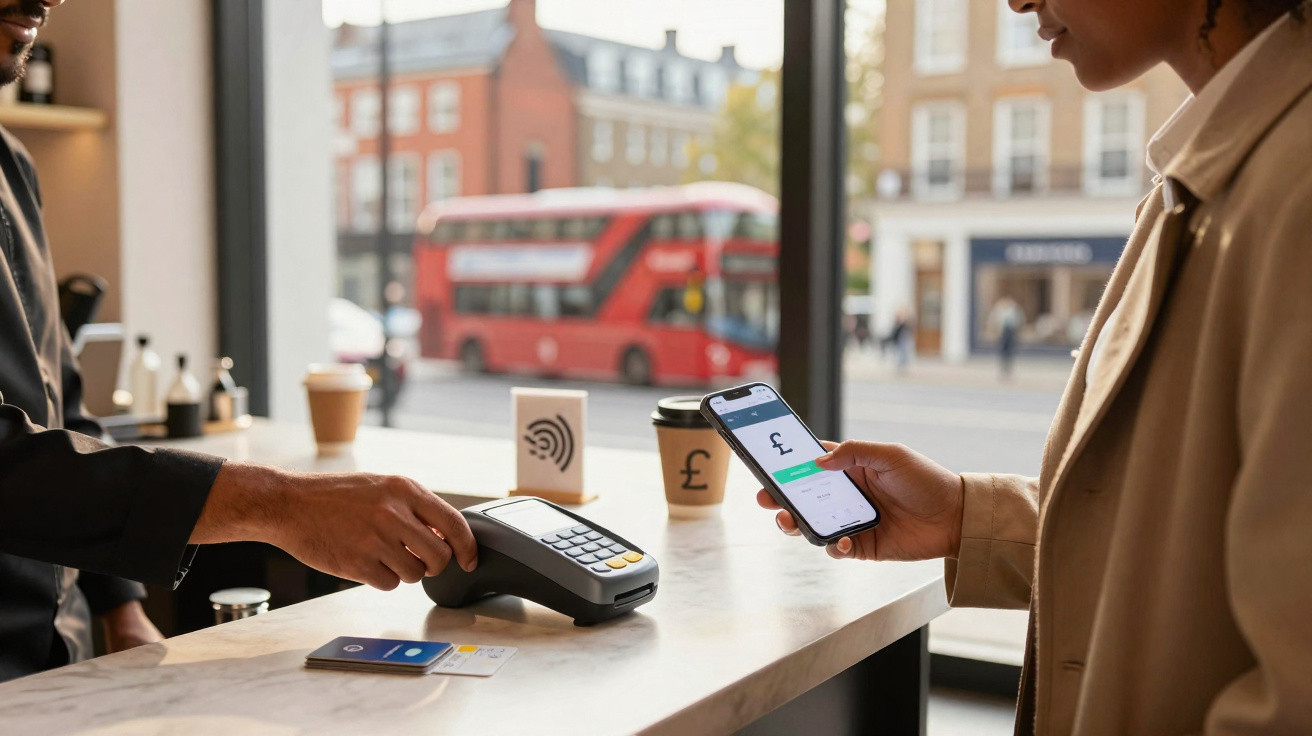
At first glance, nothing changes at the supermarket checkout: hold your card against the terminal, hear the beep, and the payment is complete. Behind the scenes, however, a key rule is changing for banks and payment providers. The UK financial regulator will now allow them to set their own contactless card payment limits, potentially well above the familiar £100 threshold where security controls are sufficiently robust.
What changes from Thursday
Until now, the maximum for contactless card payments in the UK was clearly prescribed: no more than £100 per transaction, with a PIN required for anything above that amount. The regulator has raised this ceiling gradually in recent years, in line with the technology’s rapid growth.
Under the new rules, the Financial Conduct Authority (FCA) is reversing that approach. Rather than imposing a fixed limit, it will set the boundaries within which banks may operate.
“Banks and payment providers with demonstrably strong fraud controls will be able to determine the level of their contactless card limit themselves in future – whether higher or lower.”
The main points of the new arrangement are:
- No fixed nationwide £100 limit will remain
- Institutions with robust security measures may increase the limit
- Existing customer protections will remain in place
- Any changes must be communicated clearly and in good time
The major UK banks have said they will keep the familiar £100 limit for the time being. However, they have explicitly reserved the option of following suit later if customer demand or the competitive environment changes.
Why the FCA is easing the rules
The FCA is pursuing several objectives through the reform. First, it reflects changing spending habits: more and more customers use contactless payments for almost everything, from a coffee to the weekly shop.
Inflation has also been eroding purchasing power for years. A limit that appeared generous a few years ago may now cover only an ordinary weekly grocery shop.
“The regulator wants to give institutions room to respond more quickly to inflation, new technology and customer preferences – without having to rewrite the rulebook every time.”
At the same time, the FCA is sending a clear message on fraud prevention. Any firm seeking to benefit from the new flexibility must demonstrate that its own protection systems work reliably. The expectation is that the incentive to invest will grow, because only banks with effective fraud prevention will be able to extend their limits substantially.
How widespread contactless payments are in the UK
This reform is not happening in isolation. Contactless payments have long become standard in everyday UK life. Market figures show the scale of that shift:
| Measure | Figure |
|---|---|
| Share of contactless card payments in shops (2024) | 94.6% of all eligible card transactions |
| Contactless transactions per month compared with 2015 | Around ten times as many as in 2015 |
| Contactless share for credit cards (end of 2025) | 67% |
| Contactless share for debit cards (end of 2025) | 76% |
| Average amount per contactless payment | Just under £18 |
This makes clear that the current limit is more than sufficient for the overwhelming majority of everyday purchases. The reform is aimed more at larger payments, such as electronics, clothing, restaurant bills or filling up a vehicle with fuel, where a PIN or signature is generally still required today.
Contactless card payment controls customers already have
Many UK banks have upgraded their apps in recent years. Even before the FCA relaxed the rules, customers at a number of providers were able to adjust their personal limits.
Examples from banking practice
Most major banks are retaining the £100 limit, while offering individual controls:
- NatWest, Lloyds, Barclays, Nationwide: customers can lower the limit in their banking app and disable contactless payments altogether.
- Santander, TSB, Monzo, Starling: these banks also offer flexible single-transaction limits, in some cases in £5 increments and in others through a slider that can be reduced to zero.
- HSBC and First Direct: retain the £100 limit and currently provide no app options for lower thresholds.
- Revolut: does not permit a contactless limit below £100, but does offer monthly total card spending limits.
The FCA stresses that such personal settings should increasingly become the norm rather than an added feature. Banks should actively encourage customers to set their own limits or switch the function off entirely if that makes them feel more comfortable.
What does this mean for security?
On one hand, higher transaction limits increase the risk that criminals could cause greater losses with stolen or lost cards before they are blocked. On the other, most fraud now takes place digitally, for example through phishing or the theft of online data, rather than through simply stealing a physical card.
“Legally, the position remains clear: in cases of unauthorised payments – for example following theft – banks must generally reimburse their customers, provided they have not acted with gross negligence.”
The regulator expects the possibility of higher transaction amounts to push institutions to strengthen real-time monitoring and fraud detection further. After all, every pound lost to fraud also has a financial impact on the banks themselves.
Technology on the customer side is another factor. Paying with a smartphone or smartwatch often permits higher amounts because the device actively verifies the user’s identity, for instance through facial recognition or a fingerprint. This follows a different logic from a conventional plastic card, which operates without biometric authentication.
What this means for consumers in practice
Very little will change in day-to-day life on the implementation date. Checkout limits will remain the same and terminals will work as usual. The more significant developments are likely to come over the months and years ahead, if individual banks actually make use of their new freedom.
For customers, there are three main areas to consider:
- Check app settings: Anyone who feels more comfortable with lower transaction limits should look in their banking app to see whether the limit can be changed or contactless payments can be disabled altogether.
- Turn on notifications: Push alerts or SMS messages for card payments can help identify unusual activity quickly.
- Review bank statements regularly: Report unfamiliar transactions to the bank immediately, as the right to reimbursement also depends on responding promptly.
Why this development matters across German-speaking countries
The FCA’s decision applies only in the UK, but it is likely to be watched closely across Europe. Contactless payments have also become established at great speed in Germany, Austria and Switzerland, usually with similar or slightly different limits.
Financial regulators and banks in the EU will be monitoring whether higher or flexible thresholds prove successful in the UK, whether fraud cases rise noticeably, or whether improved technology offsets the risk. If the experiment works, institutions in those markets may also push more strongly for flexible models.
Terms and background: what sits behind the limits
A number of terms surrounding contactless limits are easily confused. Three points help put them into context:
- Single-payment limit: the maximum amount for one contactless payment without entering a PIN.
- Cumulative limit: a background threshold under which a PIN is required again after several payments or after a certain total amount, even when each individual payment remains below the main limit.
- Wallet versus card: digital wallets, such as Apple Pay and Google Pay, can often process higher amounts because they add another layer of security.
Under the new FCA rules, banks will be able to adjust not only the single-payment limit but also reconsider their cumulative security mechanisms. Frequent low-value purchases could therefore be treated differently from occasional high-value transactions.
Anyone making contactless payments should not dismiss the technology as a “magic wireless chip”. Every beep involves a complex interaction between regulation, bank policy and security logic. The UK’s relaxation of the rules illustrates the possible direction of travel: greater convenience, but also greater responsibility for banks and customers alike.
Comments
No comments yet. Be the first to comment!
Leave a Comment