
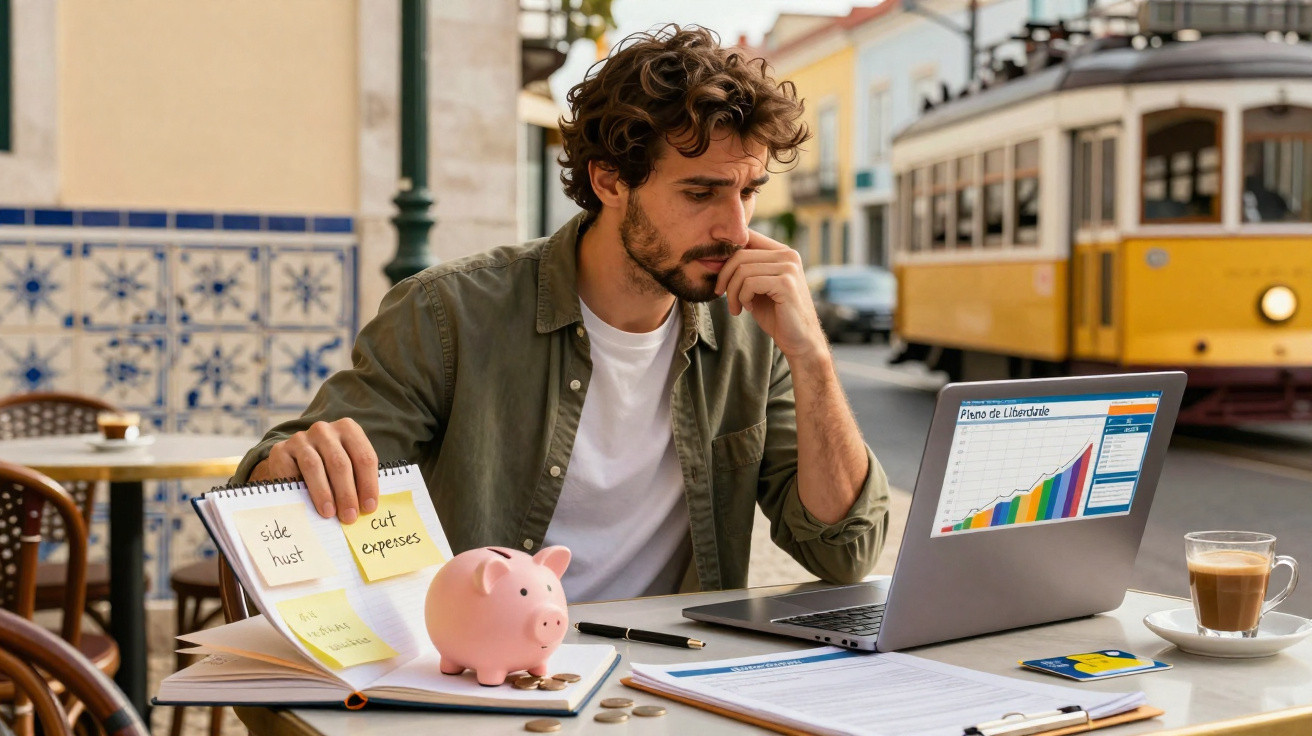
Two savings pots, three credit cards, one “high-yield” account recommended in a TikTok tip, and a vintage-jacket side hustle that largely remained in a plastic box. On the surface, she was “doing everything right”: setting up automatic transfers, working at weekends and reducing her iced latte habit. Yet every rent payment made her chest tighten, while the figures appeared never to change. After reading another thread about “building wealth in your 30s”, she felt the familiar weight of hope mixed with quiet shame.
Something in the world of financial advice does not align with how millennials actually live.
The seductive myth of “just save more” and “start a side hustle”
Open any millennial group chat and the same two messages will soon appear: save more and start a side hustle. Both sound empowering, straightforward and almost beautifully logical. There is no need to challenge the system; supposedly, all you need is a stronger spreadsheet and another income stream. The promise is that cutting back on small treats, putting the money aside and “grinding” during your spare hours will eventually purchase your way out of anxiety.
That message is everywhere: Instagram carousels, sharp, short Reels and YouTube channels filmed in minimalist flats. It is especially reassuring because it implies that you personally hold the missing lever. When the plan fails, the judgement becomes personal: perhaps you are not disciplined enough, hungry enough or organised enough.
Then, one day, you realise you are worn out, have done “all the right things”, and remain in almost exactly the same position.
Look at the figures rather than the slogans. Across the US and UK, millennial pay has lagged behind housing costs for years, while student debt and childcare costs have soared. People are saving 5–10% of salaries that were never likely to keep pace with rent, while listening to podcasts presented by people who bought their first flat before property prices shot up. A 2023 survey found that more than half of millennials with side hustles make less than $200 a month from them after costs. That is not a route to transformation; it is stress with a price attached.
Still, the story continues. Short clips labelled “day in my life: 9–5 and 5–9 grind” attract millions of views even as burnout reaches record levels. You may know someone who tried dropshipping, reselling or freelance design, only to discover that the supposedly extra job consumed their evenings and weekends for an hourly rate below that of their main role. Technically, it increased their income. In practice, it depleted their energy, relationships and capacity to rest.
The underlying issue is simple: “just save more” and “start a side hustle” are individual answers marketed for a structural problem. They shift attention from housing policy, stagnant wages, broken career ladders and late-stage capitalism, placing it instead on your everyday choices. The advice is not entirely wrong. Saving helps, and side hustles can transform lives. But as a central strategy, they are hugely overrated for a generation under pressure from forces far beyond its coffee budget.
It is like telling somebody in a leaking boat to “scoop faster” rather than questioning who made the boat and why it has so many holes.
The underrated move: changing the game, not just tightening the belt
The financial advice millennials hear least often is also the least comfortable: your real leverage isn’t frugality, it’s power. That means prioritising actions that alter the entire equation, rather than merely its edges. It could mean negotiating a 15% salary increase, switching to a role, sector or even city where your skills command 30% more, joining colleagues to push for pay transparency, or devoting the same mental effort spent monitoring outgoings to developing skills that double your rate.
This is less easy to share than advice to “skip brunch”. It is more complicated, political and uncomfortable. It requires you to challenge your manager, industry and comfort zone. But this is also where the maths begins to change. A £10,000 pay rise outweighs years spent feeling guilty about takeaways. Moving into a better-paid field can achieve more in 18 months than five years spent on a low-margin side gig you secretly dislike. Genuine leverage may look dull on Instagram and feel awkward in real life, but that is where compounding can finally work in your favour.
The second overlooked move is to create a money system that runs automatically rather than depending on willpower. This does not mean a flawlessly colour-coded budgeting app that you stop using by March. It means a few background rules that operate quietly: one current account, one emergency fund and one investment product you understand. Set up automatic transfers for the day your pay arrives, using amounts that suit your circumstances rather than somebody else’s hustle-porn fantasy. No drama and no guilt over a daily spreadsheet. Let’s be honest: nobody really does that every day.
One rainy Thursday, 29-year-old Luis sat in an open-plan Manchester office, anxious about his annual review. He had binge-watched negotiation videos, practised his lines in the bathroom and still felt as though he were pretending to be a self-assured adult. His manager skimmed his self-assessment, nodded and began with the usual corporate language. Luis took a breath and, with a slightly unsteady voice, presented three specific achievements alongside the salary bands he had researched for his role. Thirty minutes later, he left with an 8% raise.
There was nothing magical about it on paper. There was no viral side-hustle launch or “I made six figures working four hours a day” tale. It was simply a modest pay increase which, during the following year, exceeded what his freelance logo-design work had earned across two. That one discussion changed his monthly investing from “whatever’s left” into a fixed automated sum that genuinely accumulated. A few months later, he gave up the side hustle and reclaimed his weekends. The real twist was not the income itself, but the relief of no longer repeatedly exchanging time for small extras.
Stories like this rarely trend. They offer no aesthetic B-roll and no immediate dopamine rush. Nevertheless, they are closer to the real driver of financial change for most millennials: modest moves of power repeated every year, rather than endless micro-optimisation of coffee spending. When someone in a group chat says, “I asked for a raise and got it,” it may not go viral, but it subtly broadens what everyone reading it believes is possible.
Behind the polished content and tidy money hacks sits a harsh emotional trap: the claim that your finances are solely a measure of personal discipline. They are not. They are an untidy combination of choices, certainly, but also your birth year, postcode, degree subject and wider economic conditions. When a generation brought up on “follow your passion” encounters a rental market in which a one-bedroom flat consumes half its pay, switching to cheaper oat milk will not close the gap.
Overrated advice functions like a mirror angled incorrectly. It shows you the impulse purchases rather than rent rising faster than your pay. It makes you feel your “lack of hustle” rather than recognise that your sector has had no meaningful wage growth for a decade. So you intensify the only controls you believe you have: cut, grind, repeat. Real improvement begins when you stop judging yourself for failing to be perfectly frugal and start asking more difficult questions about where your time, energy and abilities could have greater impact.
What to do instead: practical moves that don’t require a second life
Begin with a straightforward exercise. In a messy notes app, if that works for you, list your three largest financial levers for this year. Not ten: three. Choose the changes that would alter your overall position. They might be “earn £5k more”, “get rid of one toxic recurring bill” or “finally start investing 5%”. Then identify the one that both scares and excites you. That should become your priority project, ahead of any side-hustle idea you will partly begin and later abandon.
Next, create a stripped-back money system around it. Let one current account receive your income. On payday, automatically send a fixed sum to a high-yield savings or investment account. Send another set amount to an emergency buffer until it reaches a figure that allows you to sleep at night. What remains is for guilt-free spending. There is no requirement to record every snack. The aim is not flawless optimisation; it is to remove constant financial negotiation from your mind, leaving that mental capacity for the major lever you selected at the beginning of the month.
Most millennials do not make the mistake of being lazy; they spread their energy too widely. One week, they are immersed in crypto threads. The next, they are fixated on Notion budget templates, before suddenly researching how to launch a print-on-demand shop. The outcome is a continual sense of beginning, with almost nothing completed. The quiet and unglamorous alternative is to select one major move and give it 90 days of serious attention, as though it were a work project. “Negotiate a raise” becomes: collect market data, document achievements, prepare a script, arrange a meeting and practise with a friend.
The same principle applies to “move to higher-paying role”: refresh your CV, apply for three jobs each week, conduct mock interviews and speak to two people already working in that field. It reads as obvious when set out like this, but life rarely feels so orderly in our minds. On a difficult day, it becomes scrolling through vacancies while half-watching Netflix and promising yourself you will “really start next month”. That is how another year goes by with the same pay and another budgeting app on your phone.
At a human level, shame is the cruellest consequence of overrated advice. You see people online saying they saved 50% of their income, built a successful Etsy shop and cleared debt in 18 months, and quietly categorise yourself as a “failed adult”. What you do not see is their full situation: family support, a high-earning partner, fortunate timing or simple survivor bias. You are seeing a highlights reel and treating it as a blueprint.
“Most millennials don’t have a money problem, they have a power problem,” says one financial therapist I spoke to. “They’ve been told to be better consumers, not better negotiators or organizers. So they feel personal guilt for structural issues, and that guilt keeps them from taking the bolder steps that would actually help.”
This is where a reframing helps. Instead of asking, “How can I save more from the same paycheck?”, consider questions such as, “How can I make this paycheck less fragile in the next two years?” or “Who else is facing the same squeeze, and what could we push for together?” That could involve unionising a workplace, joining a professional body that publishes salary bands, or simply speaking openly with friends about earnings and rent to break the isolation that keeps everyone trapped.
- Shift 1: Stop pursuing perfect savings rates and start pursuing higher-value skills.
- Shift 2: View pay rises, job changes and collective action as central money strategies rather than afterthoughts.
- Shift 3: Let automation take care of the dull parts, so your limited energy goes where it can genuinely compound.
The quiet revolution in how millennials think about money
There is something quietly radical about accepting that the standard script is not working. Perhaps you do not need another side hustle; perhaps you need a different relationship with work, power and time. Once that lands, the questions you ask yourself change. Rather than “What can I cut?”, you start to ask, “What would make this less precarious?” and “What game am I actually playing?” That shift can feel like removing shoes that were too tight without you realising how much they were hurting your heels.
Some millennials are already following this newer script, often without attaching a memorable label to it. They are the people who declined a poorly paid “dream job” for an unexciting role paying twice as much, then used the additional income to create breathing room. They are those who left a city where rent took 60% of their earnings and suddenly found they could save, travel or simply avoid panicking when the boiler failed. They are also the people who quietly stopped unprofitable side hustles and used the time to rest, learn or form relationships that later opened doors.
At a deeper level, this discussion invites us to acknowledge something we rarely say aloud: money advice is not neutral. It reflects values. The old script prizes endless individual effort, the capacity to optimise yourself into security and the notion that continued struggle means you have not worked hard enough. The emerging script values sanity, time and community. It says you are not a broken calculator because your savings rate does not resemble that of a finance influencer. You are a person within a particular system, with limited energy and genuine constraints.
Perhaps the real clickbait headline is not about overrated advice at all. Perhaps it is the quiet recognition that your life is not a productivity challenge, and your value is not determined by how many additional hours you can monetise after 6 p.m. When you next want to begin a new hustle instead of having a difficult conversation about pay, or cut back on the one pleasure that keeps you human simply to meet an arbitrary savings target, pause. Consider what could happen if you aimed less to become the perfect money robot and more to become a slightly more powerful, slightly less frightened version of yourself.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| The “savings + side hustle” myth | Presented as a miracle solution while incomes stagnate and costs soar | Understand why you can do everything “right” without seeing meaningful change |
| The real levers of power | Pay rises, job or sector changes, collective action and a simple automatic system | Identify high-impact moves instead of micro-optimising spending |
| Rethinking financial shame | Move beyond the individualistic narrative and put context back at the centre | Reduce guilt and free up energy for more strategic choices |
FAQ:
- Is saving still worthwhile if my income feels too low? Yes, but only as part of a system that does not depend on guilt and tiny cutbacks. Small automatic amounts, combined with a clear plan to increase your income, matter more than aggressive goals you cannot maintain.
- Should I give up my side hustle if it is not earning much? Keep it if it gives you pleasure or develops useful skills. If it mostly creates stress for pennies, think about stopping and using the time for rest, learning or a higher-leverage career move.
- How often should I attempt to negotiate my salary? Usually once a year, or whenever your responsibilities have clearly grown. Treat the preparation as a project: gather data, provide examples and have a specific figure in mind.
- Is investing more important than repaying debt? That depends on your interest rates and emotional tolerance. High-interest debt generally takes priority; after that, gradual investing combined with debt repayment often works better than an all-or-nothing method.
- What if I feel trapped in a low-paid field? Seek adjacent roles where your existing abilities command more value, speak to people already doing that work and allow yourself to pivot over 1–2 years rather than overnight. A gradual pivot is still a pivot.
Comments
No comments yet. Be the first to comment!
Leave a Comment