
The day my banking app went wrong, I realised I had no clue what my money was actually doing. I was queuing at the supermarket with my card ready, quietly hoping the payment would be accepted. I had been paid the previous week, but my balance had somehow dwindled. Again.
On the walk home, carrying fewer groceries than I had intended to buy, I flicked through an endless stream of transactions: coffee, subscriptions and random Amazon purchases I could not even recall making. It all merged into one draining list. There was no narrative and no sense to it - only money steadily slipping away.
That evening, at my kitchen table with a cold slice of pizza, I decided I was finished with “winging it”. I was not looking for an elaborate budget; I needed a straightforward structure. It had to work through difficult days, unproductive weeks and my very human brain. That decision changed everything.
The moment I stopped treating money as a mystery
My real breakthrough did not come from an impressive finance book or a viral TikTok tip. It came from one line I wrote in a notebook: “Every dollar I earn needs a home.”
Before that, my pay landed in my account like a guest arriving at a party without a designated seat. Rent, food, evenings out, subscriptions and impulse purchases all fought over the same pot, and disorder always came out on top.
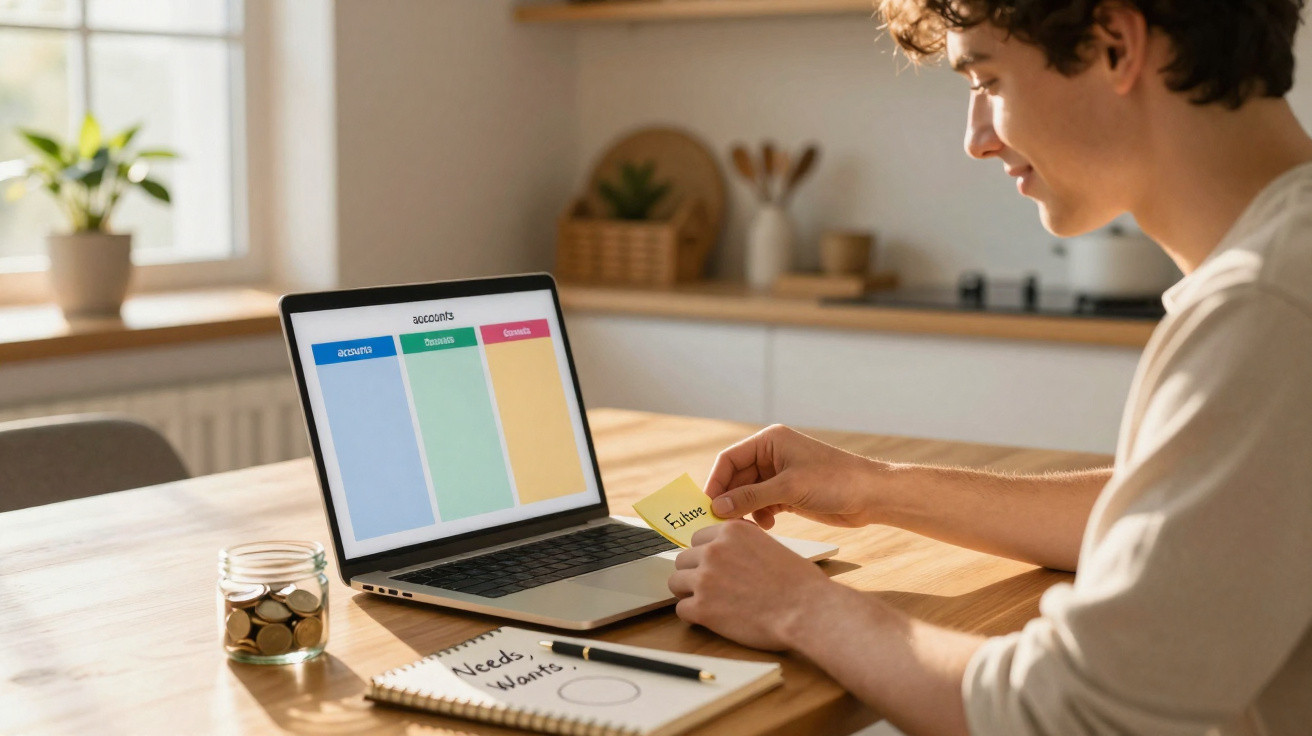
So I took another route. Rather than recording every penny, I sketched four large boxes on paper: Needs, Wants, Future and Safety. It was a clumsy, uneven version of a system, but it was a structure. It almost seemed too basic to work. Still, it was the first time the story of my money made sense.
A few weeks afterwards, I put the structure into practice properly. The morning after payday, I sat down with a coffee and four figures: 50%, 20%, 20%, 10%.
I assigned half of my income to Needs: rent, household bills, food shopping and transport. Twenty per cent went on Wants, including meals out, nights out and enjoyable extras. A further twenty per cent went to Future: savings, investments and debt repayments. The remaining ten per cent was for Safety, an emergency buffer that could quietly build in a separate account.
In my banking app, I set up straightforward spaces: one main account and three named savings pots. There were no elaborate colours or spreadsheets, just clearly labelled places for my money. For the first time, I made it to the end of a pay cycle without anxiety. It felt like finding a map after years of wandering without one.
The difference was not only in where my money went. My mind finally had a framework it could cope with amid a busy, untidy life.
Our brains do not respond well to vague instructions such as “spend less” or “be better with money”. Clear categories and uncomplicated rules work far better. When every pound or dollar has somewhere it belongs, choices become more straightforward: is this meal out a Need, a Want, or is it taking from my Future?
The structure did not magically make me rich; it simply made my choices visible. Once you can see where your money goes, you cannot stop seeing it. That small sense of discomfort is where control begins.
The simple money structure that survived real life
This is the approach I still rely on, particularly when my motivation is low. I call it my “three-account + one rule” system.
- Account 1: Daily Life. All my Needs and essential bills come out of this account.
- Account 2: Fun & Flex. This is the home for my Wants. Once it is empty, the fun stops.
- Account 3: Future & Safety. This holds savings, my emergency fund and additional debt payments.
The one rule is simple: money does not move backwards. Once it has left Daily Life for Future & Safety, it cannot return to fund late-night takeaway. That small boundary protects me from the exhausted version of myself who scrolls at midnight - the version most likely to undo good intentions.
Many people become trapped in the search for a “perfect system”. They wait until they have read the right book, discovered the ideal app or worked out every percentage. In the meantime, their money carries on doing whatever it wants.
Honestly, no one manages this perfectly every day. You will not log every expense for the rest of your life, and you will not always turn down drinks or cook rather than ordering food.
Instead, create a structure that allows for that. Set up automatic transfers immediately after payday, even when the sums seem modest. Give your accounts names that make sense to you rather than to a financial expert. On difficult days, allow yourself to be human while your system quietly maintains the boundary in the background.
One sentence transformed the way I speak to myself about money. I still repeat it whenever I am tempted to ignore my own rules:
“Future-you is already paying for today’s choices. The only question is how expensive you want that bill to be.”
To make the system practical rather than theoretical, I keep a small “money cheat sheet” on my fridge:
- Choose no more than 3 pots: Daily, Fun, Future
- Set straightforward percentages rather than perfect ones
- Automate transfers on the day your income arrives
- Never take from Future to pay for Fun
- Review it once a month with a coffee, not guilt
It does not look particularly impressive in a spreadsheet. However, this simple, low-tech structure takes on the emotional hard work on days when my willpower is somewhere between tired and non-existent.
The calm that comes when money has a clear shape
There is usually a point, around three or four months in, when this sort of system begins to feel unexpectedly ordinary. You no longer check your balance with a knot in your stomach. You begin to spot your own habits: the mid-month dip, the Friday-night splurge and the “I’ve had a difficult week” shopping.
What surprised me most was not that I spent less. In some months, I did not. The change was that every pound or euro felt less chaotic. My Wants no longer competed with my rent. My Future was no longer vague or distant; it had its own quiet place in my banking app, growing in small but persistent amounts.
We have all had that moment when we are scared to open our banking app because we already know the result will not look good. A simple structure will not remove that feeling overnight. It simply gives you a gentler landing and a clearer next step.
Your questions begin to change. Instead of asking, “Why am I so bad with money?”, you ask, “Which pot is out of balance this month, and what small adjustment can I make?”
That is the real power of structure. It does not make you flawless; it makes you truthful. From there, your finances can gradually become less of an anxious fog and more of a clear story that you are deliberately writing.
| Key point | Detail | Value for the reader |
|---|---|---|
| Simple pots are better than complicated budgets | Use 3–4 distinct categories: Needs, Wants, Future, Safety | Simpler decisions, reduced stress and fewer “where did it go?” moments |
| Automation instead of willpower | Transfers take place straight after payday, with no daily discipline required | Progress continues during lazy, busy or stressful weeks |
| One protective rule | Money never moves from Future back to Fun | Creates an emergency cushion and long-term security without continual effort |
FAQ:
- Question 1 How do I begin if my income is irregular? Base your pots on your lowest “typical” month rather than your best one. When you earn more, send the extra to Future & Safety first, then top up Fun if every essential cost is covered.
- Question 2 What if my Needs already take up almost all my income? Begin with very small percentages: even 5% for Future & Safety is better than nothing. Then consider the biggest costs: housing, transport and debt. Sometimes one difficult adjustment brings the real change, rather than a hundred small sacrifices.
- Question 3 Do I genuinely need several bank accounts? No. You can use “spaces”, sub-accounts or even a notebook if your bank offers only basic features. The important part is the mental separation: your brain needs to recognise that Fun and Rent are not drinking from the same glass.
- Question 4 How long does it take to feel natural? Allow three pay cycles. The first month feels awkward, the second is for experimenting, and by the third it begins to feel like a routine you do not want to lose because you can finally see small wins.
- Question 5 What if I make a mistake and use my Future money? It happens. Notice the moment, forgive yourself and restart the rule from the next payday. The aim is not perfection; it is having fewer “rescue missions” from your Future as each month passes.

Comments
No comments yet. Be the first to comment!
Leave a Comment