
The email lands between a pair of spam promotions and an energy bill.
Its subject reads: “Changes to the taxation of your savings accounts.”
Most recipients open it while queuing at the supermarket or relaxing on the sofa, watching television with one thumb scrolling on their phone.
Initially, the language seems dry and technical: “New rate”, “withholding”, “from next month”. Then one sentence stands out: the government has confirmed that a new tax will be deducted directly from bank savings.
That modest reserve of money, meant to stay secure and build up quietly over time.
Now, a portion will be removed before it even reaches you.
The day the rules changed for ordinary savers
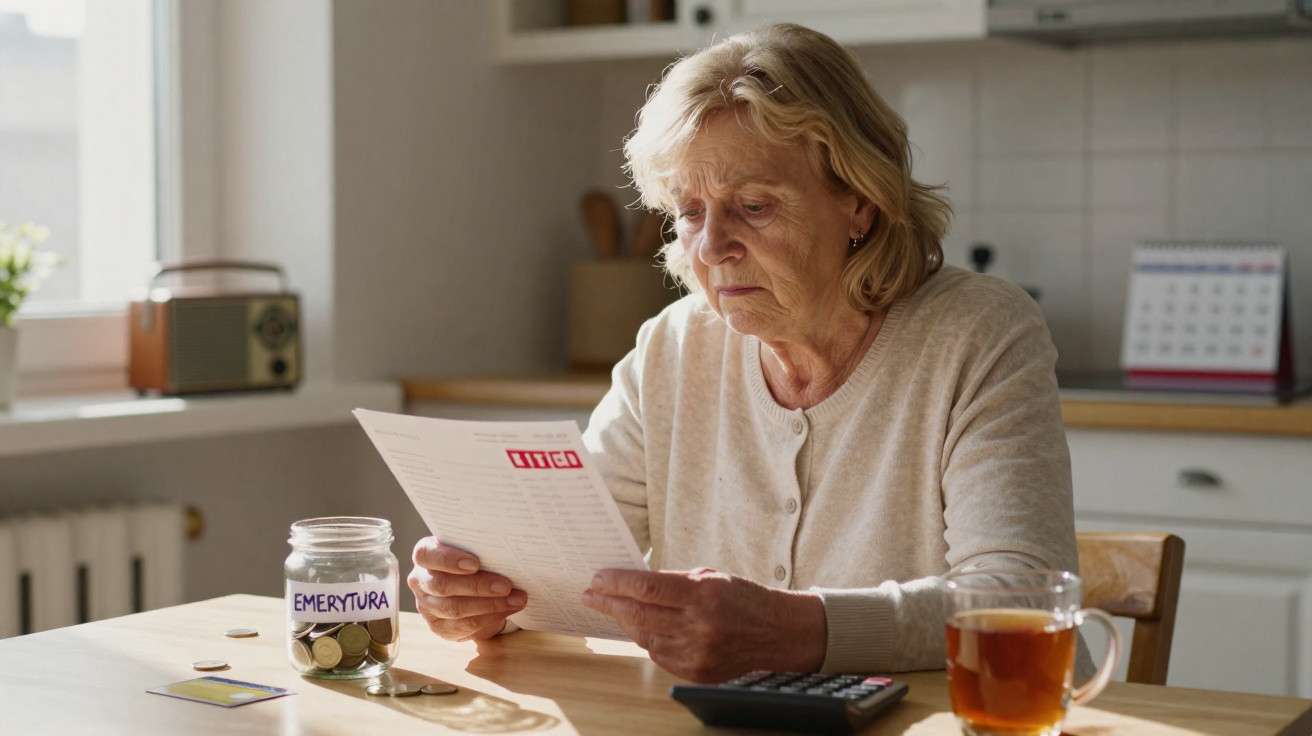
Imagine Margaret and John, a retired couple, at their kitchen table with mugs of tea and a bank statement printed out in front of them.
They are neither investors nor speculators, and they are not gambling on the stock market.
They are simply two people who spent four decades saving small amounts whenever they had the chance.
A new entry is visible on the statement: “Tax on savings interest – debited”.
It is not an enormous sum: £18.74 this month. Yet they exchange a silent glance, both considering exactly the same question.
If it is £18 this month, how much might it amount to in a year, or in five?
The rules have shifted.
And they had no say over the fine print.
On paper, what the government has announced is straightforward: interest earned in bank accounts will face a new tax, applied automatically from next month.
There is no form to complete and no option to select. The deduction will happen before the money ever reaches your hands.
For millions of pensioners and everyday savers, this means that interest above the existing allowance will partly be channelled to the Treasury.
The declared aim is to “broaden the tax base” and “better align the treatment of capital and labour income.”
They are weighty phrases that can sound reasonable at a press conference.
Yet, in practice, a further share of the burden will quietly fall on savings held by teachers, nurses, self-employed people and factory workers long since retired.
Those who follow the rules can feel, yet again, that they are the simplest people to target.
The government's case is clear enough: public finances are under strain, debt levels are elevated, and an ageing population is increasing pressure on healthcare and pensions.
Taxing savings interest can appear to be a tidy technical answer.
It will not appear as a major new tax on a payslip, while the payments are dispersed across millions of separate accounts.
Viewed from afar, it is almost impossible to notice.
Viewed at close range, it is very noticeable when bank interest helps to supplement a small pension or meet increasing rent.
In truth, hardly anyone reads every single line of a Finance Bill.
This rule does not depend on whether anyone has read it, however. It is embedded in the system, taking a portion of every pound of interest as soon as it is paid.
That is why many savers feel less like citizens and more like another entry on a spreadsheet.
How to respond to the new savings tax without panicking
After the initial surprise has passed, the issue is practical: what can you genuinely do about the new tax?
The least helpful choice is to ignore it for three years, only to discover later that more of your savings has disappeared than you had anticipated.
Begin with a dull but effective task: make a list of every savings account you hold and the rate of interest each one pays.
Include more than your main bank account; remember the old account opened ten years ago “just in case”.
Then make a rough calculation of your yearly interest and set it against the tax-free allowance that remains available to many savers.
If you are near the threshold or already above it, you need to decide what to do.
You could divide your money among different products, or seek accounts that are still protected from this new tax.
One quiet evening spent with a calculator could be worth hundreds of pounds over the coming years.
One common reaction is to withdraw everything from the bank and keep it as cash, “so they can’t touch it”.
That may feel like resistance, but it brings different dangers: theft, loss and inflation steadily reducing its worth.
You may avoid the tax while seeing your purchasing power fall month after month.
Another regular error is pursuing the top interest rate without checking the terms.
Some “promotional” accounts appear attractive but tie up your funds for lengthy periods or impose charges when you need access to them.
For people with limited incomes, pensioners in particular, being able to access money easily can matter more than gaining an extra 0.3%.
We have all had that experience of agreeing with banking jargon merely to avoid asking, “Wait, what does that actually mean?”
This is one of the occasions when asking precisely that could genuinely save you money.
A financial adviser I spoke to put it bluntly: “This new tax won’t ruin the rich. It will nibble away at the cautious, the careful, the ones who quietly saved instead of spending everything.”
He identified three straightforward steps that ordinary savers can weigh up without venturing into anything unfamiliar or alarming:
- Move some savings into tax-advantaged accounts that are still available under the new rules, even where the limit is lower than it used to be.
- Diversify cautiously: combining instant-access savings with low-risk bonds may reduce the tax impact while keeping funds available.
- Check your accounts annually, ideally when you review your energy tariff or insurance, so that nothing is left unchanged for a decade.
None of this turns you into a day-trader. It simply means you’re not leaving free money on the table in a system that already takes enough.
A small amount of awareness is always better than complete trust.
Beyond the figures: what the new tax says about the social contract
Looking beyond the calculations, this new tax suggests something more profound about society's treatment of smaller savers.
These are not people who profited from huge rises in property values, complicated tax arrangements or corporate bonuses.
They are the steady, reliable sort: people who saved for Christmas, a broken boiler or the possibility that work might unexpectedly end.
For many, the interest earned on savings is not a “bonus”.
It can mean turning the heating up by one degree during winter, or being able to help a grandchild with a deposit.
When that interest is taxed, those small but deeply human choices become harder to make.
The simple reality is that confidence in institutions was already fragile.
Every quiet charge and every unexplained entry on a statement weakens it a little further.
Some people will adjust without complaint. Others will feel that their understanding of the arrangement with the state - work, save, act responsibly and be respected - has been altered in silence without their agreement.
| Key point | Detail | Value for the reader |
|---|---|---|
| Understand what is taxed | The change affects only interest above the existing allowance, with the bank deducting tax at source. | Allows you to assess the true effect on your monthly and annual income. |
| Map your savings | Record every account, its rate and its annual interest, including accounts that are old or easily forgotten. | Provides a clear overview, allowing you to move money to products treated more fairly. |
| Make calm adjustments | Use tax-advantaged products, diversify cautiously and reassess your arrangements once each year. | Limits the tax's long-term impact without taking irresponsible risks. |
FAQ:
- Question 1 Will the new tax affect every saver, regardless of how small their account is?
- Question 2 How will the new tax appear on my monthly bank statements?
- Question 3 Will pensioners or households on lower incomes receive any particular protection?
- Question 4 Should I transfer my savings into investments such as shares to avoid this tax?
- Question 5 Could the government raise this tax again in the future if public finances deteriorate?
Comments
No comments yet. Be the first to comment!
Leave a Comment