
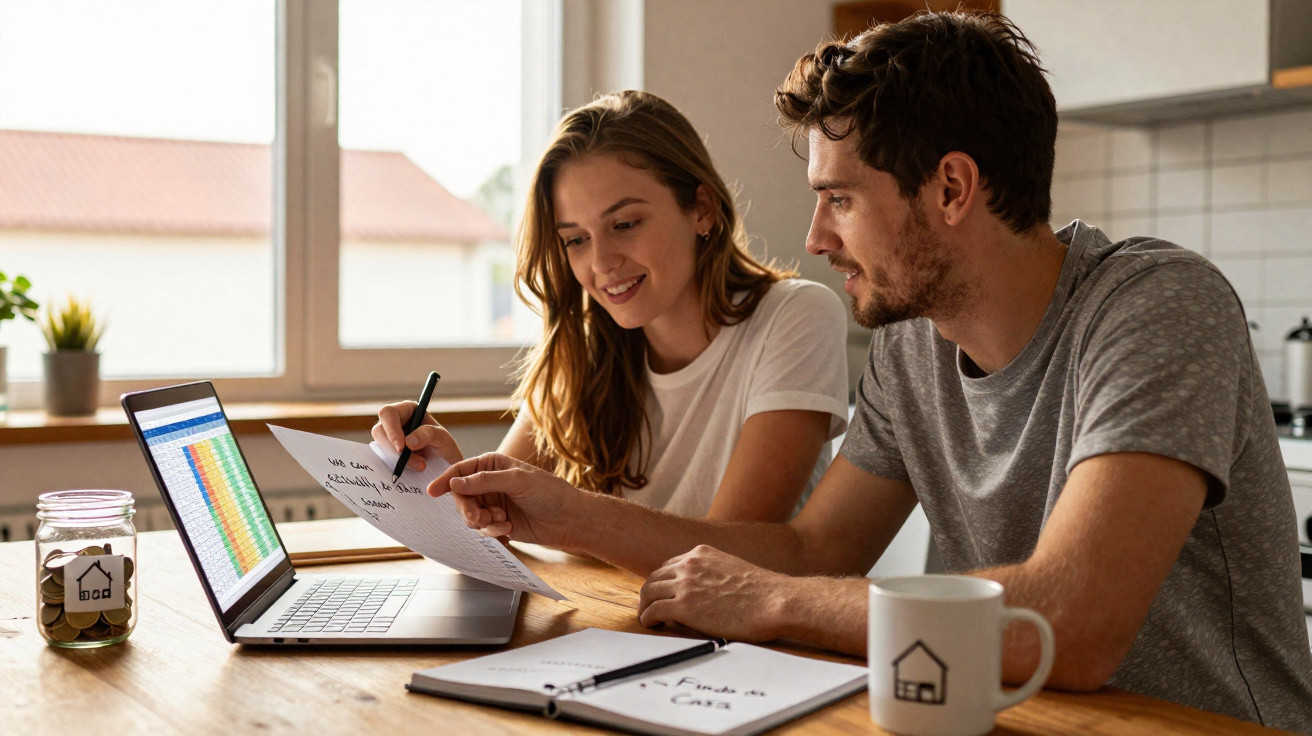
It was a Tuesday evening in a rented flat, with a bathroom extractor fan that sounded like a light aircraft.
The floor tiles were freezing, the walls so thin they could hear a neighbour’s kettle click off, and the newest rent increase was sitting on the kitchen table. The figure had been circling their thoughts all night. Ella drummed a pen against a wine cork while Jamie looked at the fridge as though it might swing open and offer them a deposit. They were both putting in the hours yet getting nowhere, a particularly British form of being stuck. Eventually, they faced a truth that had nothing to do with bravery or positive thinking: they needed a different way to pay rent. Once they gave it a go, their house-buying timeline leapt forwards in a way that almost seemed unfair. The surprising part? It was not an app. It was the sequence in which their money moved.
The night the spreadsheet became a promise
They named the approach “Rent to Us.” It was not a vision board or a budget spreadsheet containing fifty tabs. It was one choice: every payday, part of their income would go into a “Home Pot” before they even saw it, as though they were paying rent to their future selves. Making that transfer first mattered more than any coffee they chose not to buy. It reset the starting point. If the money has left before you can spend it, the rest of the month has to adapt to the balance that remains.
Rather than choose a pound amount, they chose a percentage, because pounds can spark arguments. Percentages felt more impartial. They settled on 45% of their combined take-home pay, which initially sounded ridiculous until they worked through every other figure. Their rent, bills and everyday lives had to fit into the other 55%, and although it was uncomfortable for several weeks, their routines eventually adjusted to the new normal, much as eyes adapt in low light.
What “Rent to Us” actually means
This was the structure they arrived at. On payday, their money automatically divided into two routes: 45% went to a “Home Pot” held with a separate bank, while 55% stayed in the account used for everything else. The Home Pot paid into two Lifetime ISAs, one for each of them, because free money is still free money. They also created a modest emergency buffer, an unglamorous measure that required plenty of resolve. Each quarter, they increased their saving rate by 1% without bringing it up with one another, since small adjustments were less likely to cause an argument.
They thought of the transfer as rent due on their future front door. That language was useful whenever either of them felt tempted to dip into the pot for festival tickets or an expensive blender. Rent cannot be negotiated. Meanwhile, the government bonus inside their LISAs became a quiet accomplice. A LISA is not a trick; it is simply a boost that works alongside discipline.
The mechanics that make the plan liveable
Automation handled most of the emotional labour. They arranged standing orders with the bank, and the money then moved each month without fuss. They also held a ten-minute weekly “money date” on Sunday evenings, giving themselves just enough time to decide whether they could say yes to one social plan or two. In truth, nobody keeps up this kind of check-in every day. Ten minutes once a week is the sweet spot: enough structure to avoid regret, while leaving room for spontaneity.
They also allowed themselves separate pockets of freedom. At the beginning of each month, a small “fun allowance” for each person went on to an individual card. Once that balance was spent, the decision about taxis or drinks had already been made. There was no drama and no guilt induced by spreadsheets. Because they had also built an emergency buffer for dull disasters, they did not need to touch the Home Pot when the washing machine began making a grinding noise like a fork in a blender.
The Sunday sweep
On Sunday night, any money remaining in their spending account above an agreed threshold was swept into the Home Pot. These were not dramatic deposits, merely little transfers: a quiet £28 one week, £63 another. Over time, those small scoops accumulated into something tangible, like the moment coins in a jar unexpectedly start to feel weighty. The ping confirming a transfer became a small source of pride.
The LISA booster that multiplies their effort
As they were both under 40, they each opened a Lifetime ISA. They could each pay in up to £4,000 per year and receive a 25% bonus of up to £1,000 annually. For two people, that meant £2,000 a year in bonuses simply for staying consistent. They chose providers they found manageable rather than those advertising the flashiest rates, because a simple system was one they would genuinely maintain. Patience was necessary too, as an account must have been open for at least a year before it can be used towards a first home.
The restrictions were important as well. Unless you are buying your first home for up to £450,000, are over 60, or meet particular circumstances, LISA withdrawals carry a 25% penalty. That charge discouraged them from touching the money whenever temptation appeared smiling. Having two LISAs also lifted their spirits in difficult weeks. One would say, “At least the government’s chipping in,” which made the other laugh. Sometimes, motivation is simply the sense that you are not doing it on your own.
Dual Lifetime ISAs make the government a quiet teammate, contributing 25p for every £1 you manage to save. It is not spectacular, but it builds up in the way small pushes do. Pair that with taking rent-day money from your own income first, and the whole month changes shape. Money starts to serve you before anything else.
Stopping lifestyle creep without hating your life
When a pay rise arrived, they used “raise and freeze.” They allowed themselves a small taste of the extra income, then sent everything else directly into the Home Pot. Three months later, they considered whether they had missed it. Usually, they had not. Lifestyle creep resembles ivy: attractive at first, but quietly capable of taking over the entire wall.
They also adopted a “threshold treat rule.” Whenever the Home Pot reached another £5,000 milestone, they gave themselves one treat that was wonderful but limited: a visit to the good ramen restaurant, a train day trip to the coast, or a new duvet that did not battle them at bedtime. Marking progress towards the deposit without setting fire to it helped them continue. If you preserve joy, you preserve momentum. Discipline with oxygen lasts longer than grit with no air.
The rent renegotiation trick
Many people treat rent as fixed, but it is not always. They asked for a 12-month renewal with a small rent reduction, offering to deal with the leaking window themselves in return for staying where they were. Their landlord valued dependable tenants just as much as they valued a predictable bathroom fan, so they agreed. Saving £40 a month did not look transformative at first, until it did.
They also relocated one bus stop farther away, where the pavements had less shine. That decision reduced their monthly costs by a further £240, while extending the commute by six minutes. In the mornings, the small bakery near the station made the area smell of bread, which made the compromise easier. The full £280 monthly difference went directly into the Home Pot. That is the power of moving rent even slightly: the figures gather speed.
Windfalls and side quests
They gave “spiky money” a destination. Tax repayments, wedding gifts tucked inside envelopes, occasional bonuses, and the £90 earned from selling a spare bike whose chain had rusted pink all went to the Home Pot on the day they arrived. Money travels quickly when it has a route already assigned. It also stops seeming magical and starts becoming mathematical.
One wet Saturday, they held a car boot sale that carried a faint scent of diesel and cinnamon buns. They laughed when the first item sold was a retro lamp Jamie had disliked since 2017. They made £146 in total, money that would previously have slipped away through takeaways and taxi fares. Instead, they took it straight to the bank and watched their balance rise. Small victories that hum rather than shout are often the ones that endure.
The wobble, because there is always one
Three months into the plan, the car clutch failed like a stubborn old bull. The repair bill took the wind out of them. This is where most saving plans collapse, since a plan without a buffer is merely a dare. Their emergency pot covered the cost, and the Home Pot remained untouched. It was not heroic; it had simply been decided in advance.
We have all experienced the moment when a bill arrives and the brain starts fizzing. That is exactly when you need a plan capable of surviving your emotions. Their rule was straightforward: the Home Pot could never be broken into, not even at Christmas. They reduced the gifts, not the dream. After that setback, their confidence became stronger. They had evidence that their system could withstand a blow.
The figures that cut three years away
Put the numbers on the table like cups and saucers. Their combined net income was around £4,800 per month. From the first day, they directed 45% to the Home Pot, equalling £2,160 each month. The renegotiated rent and the move one stop farther out added £280 a month to this amount. Across the year, their two LISAs provided £2,000 in bonuses. They also increased their saving rate by 1% each quarter, moving from 45% to roughly 49% over the year without any fuss.
Over twelve months, the Home Pot received about £26,000 in monthly transfers, alongside £3,360 from the lower rent, plus a £2,000 LISA bonus. Add a modest £1,200 from windfalls and Sunday sweeps. That came to just over £32,000 in the first year. Year two accelerated because pay rises were frozen into the pot. By month 28, they had passed £60,000, enough for a 10% deposit and fees on a starter flat that did not make their souls wilt.
What might the alternative version of their lives have looked like? Had they saved only “what’s left” after each month had done its damage, they estimated they would have managed perhaps 20% of their take-home pay, around £960 a month. Even with the LISA bonus, that route appeared to mean five years of slow saving for a similar deposit. Their own route lasted a little over two years, cutting almost three years from the wait. Three years faster is not magic; it is the maths of paying yourselves rent first, securing the LISA bonus and turning the dial up every quarter.
Try the maths yourself, gently
Choose a deposit figure that covers 10% plus fees in an area that feels right, rather than the postcode your boss selected. Write down your combined take-home pay, then pick a percentage that feels frightening but manageable for three months. If you qualify, open two LISAs and arrange the standing orders before you have time to reconsider. Add a small quarterly increase, just 1% at a time. Then guard the Home Pot as though it were a sleeping cat: do not prod it merely because you feel restless.
How it felt on key day
Completion took place on a rainy Thursday smelling of fresh paint and wet cardboard. The estate agent’s office served poor coffee that somehow tasted like victory. They held their keys as if they might float away. When they entered their flat, the silence sounded unlike rented silence. They opened a window simply to listen to their own hinges creak. For the first time in years, the bathroom fan no longer sounded like an aeroplane; it sounded like a future.
Their happiness was not fireworks. It was found in small things: a shelf where books could finally sit without a landlord’s permission, and a hook by the door for a coat that would stay there for a decade. They were not property tycoons. They were two people who changed the order of their money and waited. The waiting seemed shorter because every month brought a small win. The Home Pot had become walls, a roof and a silly disagreement over where the kettle should go.
A one-month “try it on” plan
Give it a four-week trial. On your next payday, set up a standing order that sends a bold percentage to a separate bank. Label it “Home Pot” in your banking app so your brain understands its purpose. Open a LISA each if you are eligible, even if you put in only £50 to start the clock. Set a spending-account threshold that keeps you honest, then sweep any amount above it on Sundays. Each week, take one short walk together and say aloud what you want your front door to look like.
Do not chase perfection. Look instead for a proven change: rent paid to your future self becoming the first bill you settle. You are not aiming for smugness; you are looking for momentum. A good plan survives bad weeks. If the percentage is too ambitious, lower it slightly while keeping the system in place. A sustainable 38% is better than a heroic 50% that falls apart at the first birthday invitation.
The small, stubborn truth
The method that removed three years from their timeline was not a secret market manoeuvre or a colour-coded budget. It was the order in which money left their account. Pay yourselves rent first. Let the government add 25% through a LISA while you get on with life. Increase the percentage as you would adjust a dimmer switch, rather than flicking a light on and off. Protect the pot, celebrate milestones and keep a modest emergency fund ready to absorb life’s clumsy elbows.
Most couples do not need a miracle; they need a system they do not have to think about when they are tired. Once that system is in motion, the deposit stops looking like a mountain and starts resembling a staircase. You then climb it one payday at a time, until the key turns and the hallway light is finally, gloriously, yours.
Comments
No comments yet. Be the first to comment!
Leave a Comment