
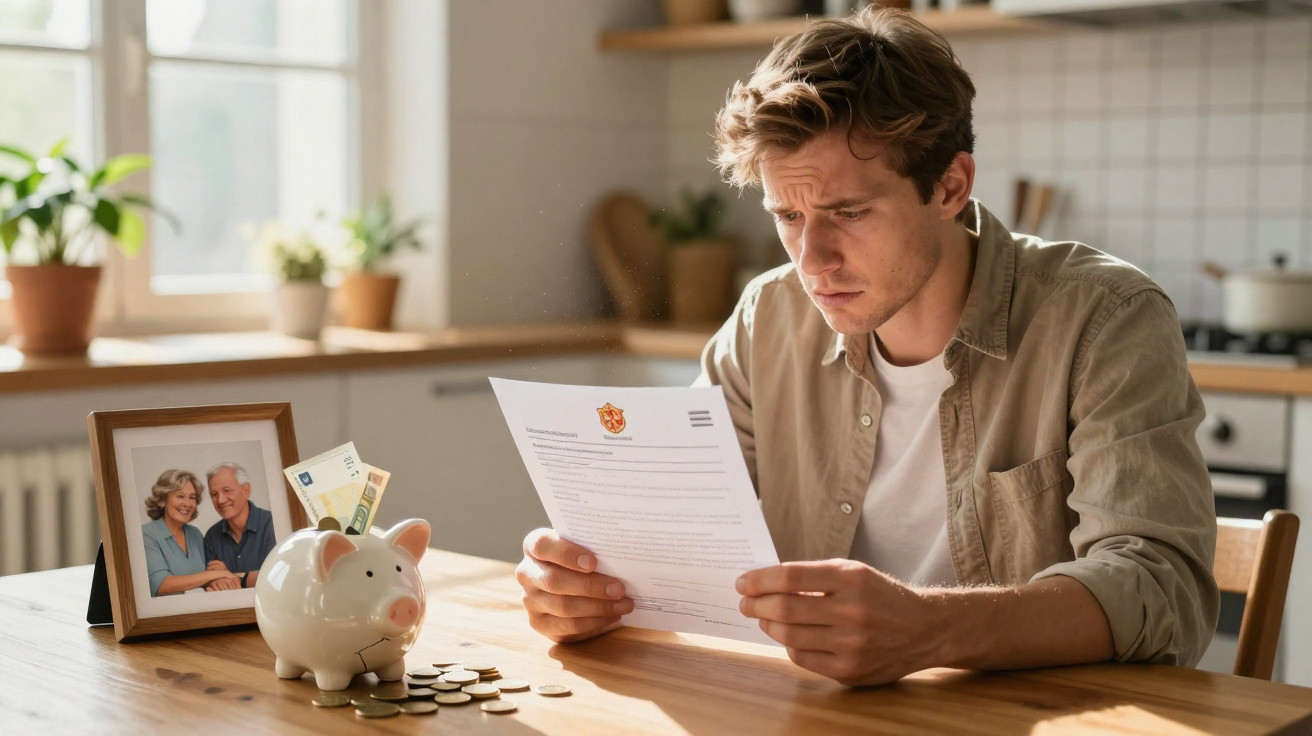
On a bleak January morning in a tiny solicitor’s office, Emma found herself looking at a bill she had never imagined receiving. Her father, a former engineer, had spent 40 years forgoing breaks, saying no to takeaways and putting money into ISA accounts rather than increasing the heating. When he died, he was proud that he had “left something behind” for his only daughter.
That “something” was now being divided up by a tax system she had never considered, until it crashed into her life like a cabinet full of files toppling over.
There were no luxury handbags or hidden investments: only a modest home and cash saved with care. But the probate office letter felt more like a demand for payment.
Inheritance tax due on the estate. Extra valuation checks. Deadlines. Interest.
Emma’s bereavement had abruptly acquired a cost, set out in tidy HMRC typefaces and legal terminology, with references to “changes taking effect January” that nobody in her family knew existed. Looking down at her father’s old, creased savings plans on the desk, she felt almost betrayed.
Across the UK, comparable experiences are emerging as families encounter the harsh consequences of January’s inheritance law changes. Those raised to save, purchase property and make plans are finding that the apparent reward for doing everything “properly” can be a larger tax bill for their children.
Officially, it is a matter of thresholds, allowances and “fiscal responsibility”.
For those living through it, it can seem like a stealth tax on affection, remembrance and the everyday sacrifices that created those savings.
When saving for your children becomes an inheritance tax trap
Inheritance tax was once portrayed as a levy aimed only at the extremely wealthy: families with their names on library extensions and second homes in the Alps. That picture is rapidly falling apart.
Since January, an increasing number of estates have been caught, not because households have suddenly become wealthier, but because property prices have risen while tax thresholds have remained fixed. Frozen allowances are effectively delivering a tax increase without any change to the headline rate.
Consider a semi-detached home in a commuter town bought for £130,000 in the late 1990s. Today, that same house could be worth £550,000 or more. Add a couple’s combined savings and perhaps a modest pension pot, and their estate can quickly approach or exceed inheritance tax limits.
Relatives are often shocked to learn that the house in which they grew up is treated as a taxable asset rather than simply a legacy. The January rules on reporting and valuations are affecting these “ordinary millionaire” households most severely, particularly in the South East and major cities.
This is the point at which the term “stealth tax” carries real weight. As the main rates have not changed, politicians can argue that nothing significant has occurred. But by holding tax-free thresholds still while earnings and prices have moved upwards, the system brings more people into scope each year.
It can feel less like a tax on wealth and more like a tax on people whose parents happened to buy property at the right point in time.
Children are not being penalised for careless spending, but for their parents’ self-discipline.
January inheritance tax rules that take families by surprise
January has brought increased attention to detailed estate reporting, including lifetime gifts and property valuations. In principle, the aim is to close loopholes and ensure fairness. In practice, families face paperwork resembling a forensic examination of an entire life.
The £5,000 your parents contributed towards a car? Money transferred for your wedding? The “loan” that was never genuinely expected to be repaid? Each may now be relevant when calculating inheritance tax.
Many people face this without preparation. Inheritance law is rarely discussed over Sunday lunch while parents quietly move money into savings accounts “for the kids”. Gifts made during the previous seven years can unexpectedly return to the picture, and not with any sense of fond nostalgia.
When a parent dies in winter, their lifetime generosity can be scrutinised through forms and tables. That is before the updated checks on property values are considered, which, as part of this January drive, are pushing borderline estates into taxable territory.
In truth, almost nobody maintains a flawless record of every gift made to loved ones over 10 years. The new climate approaches that untidy human reality as though it were an error to be fixed.
For the state, however, such complexity creates income. A frozen nil-rate band, tighter reporting requirements and a firm expectation that assets are fully valued combine to form what critics describe as a tax rise by stealth, particularly for family homes.
What was once vague conversation about “passing things on” has become an exercise in spreadsheets, with a bill at the end.
How families can reduce the shock before it arrives
A single understated step can make a major difference: talk openly with parents, while they are alive and well, about what they own. This need not be an acquisitive discussion about “what’s in it for me”, but a measured and practical conversation.
Make a list of assets, approximate values, unpaid debts and any substantial gifts made in recent years. Cover the obvious items, such as the home, as well as ISAs, Premium Bonds and the old life insurance policy nobody has reviewed for years.
After that, seek professional assistance. One appointment with a solicitor or tax planner can outline a strategy suited to the family’s circumstances. It could involve using the residential nil-rate band, placing life insurance in trust or preparing a straightforward will that does not inadvertently create additional tax. A lot of damage is done by DIY wills that seemed “good enough” at the time.
The modest, unglamorous task of organising documents now could spare children a five-figure bill later.
Most of us know how tempting it is to put off a difficult conversation about money rather than begin it. Families postpone it. Parents respond with “oh, it’ll be fine” before changing the subject. Then January-style changes arrive, and the system is unforgiving towards those who have not prepared.
The simple reality is that the taxman has no emotional investment in your bereavement.
“People think inheritance tax is about greed at the top,” one London probate lawyer told me. “What I see is nurses’ children, retired teachers’ children, paying tax because their parents owned a house in a rising market and trusted the system. They didn’t realise that doing ‘the right thing’ made their estate vulnerable.”
- Begin the discussion early – Discuss assets and intentions while parents are healthy and able to make clear decisions.
- Have a proper will prepared – Do not rely on low-cost templates that overlook inheritance tax thresholds and residence rules.
- Record significant gifts – Note anything above the small gift exemptions, particularly gifts made in the final seven years.
- Review life insurance policies – Explore placing them in trust so that payouts do not increase the taxable estate.
- Revise plans following legal changes – Use major fiscal announcements and January rule changes as prompts to reassess all arrangements.
Beyond the figures: what this “stealth tax” reveals about us
Every inheritance tax form represents a kitchen table and a box of photographs on the floor. Someone is sorting through documents with one hand while wiping away tears with the other. This is the unvarnished reality missing from charts about frozen thresholds and projected tax receipts.
When children receive substantial tax demands because their parents lived frugally and saved, it raises an uneasy question about what the system actually rewards.
Some believe that abolishing inheritance tax completely would only reinforce wealth inequality. Others maintain that the present system already has that effect, taxing modest estates in overheated property markets while the very wealthy employ specialists to navigate around the rules.
The January changes have not prompted mass protests or late-night television arguments. Instead, they have quietly created a feeling of injustice among thousands of ordinary families who believed they had followed the rules.
Perhaps the central question is not “Is inheritance tax right or wrong?” but “Who do we think deserves to keep the fruits of a lifetime of restraint?” When the response appears disconnected from the everyday experience of people such as Emma, trust begins to weaken.
The law may describe it as revenue. Children will remember it differently when they write a cheque on top of the funeral costs. That distance between the law and personal feeling is where resentment over this so-called stealth tax is only starting to build.
| Key point | Detail | Value for the reader |
|---|---|---|
| Frozen thresholds bite | Tax-free bands have not kept pace with property prices, drawing more “ordinary” estates into inheritance tax | Helps readers see why their own family may now be at risk, even without substantial wealth |
| January rules tighten checks | Since January, greater scrutiny of gifts, property values and reporting has increased the effective tax take | Warns readers that they need records and professional advice before a death takes place |
| Planning can soften the hit | Early discussions, current wills and effective use of allowances can legally reduce the bill | Provides readers with practical measures to protect children against unexpected tax demands |
FAQ:
- Question 1 Why are more people calling inheritance tax a “stealth tax” this year? Because frozen tax thresholds and stricter January reporting rules are increasing how much tax is collected, without any headline rate rise that would usually trigger public debate.
- Question 2 Has the actual inheritance tax rate changed in January? No, the main rate remains the same, but the real burden has grown as more estates are dragged above the unchanged tax-free allowance, especially where property values have jumped.
- Question 3 My parents only have a house and some savings – do we really need to worry? If their total estate value, including the home, approaches or exceeds the available allowances, then yes, it’s worth getting advice, because seemingly modest estates can now tip into taxable territory.
- Question 4 Do gifts given while my parents are alive still count toward inheritance tax? Gifts made in the seven years before death can be pulled back into the calculation, especially larger ones, which is why tracking them has become more crucial under the January emphasis on detailed reporting.
- Question 5 What’s the first practical step to protect my family from a shock bill? Arrange a simple meeting with your parents and a solicitor to review their assets, their will, and how the current inheritance tax rules-including the new January expectations-apply to their situation.
Comments
No comments yet. Be the first to comment!
Leave a Comment