
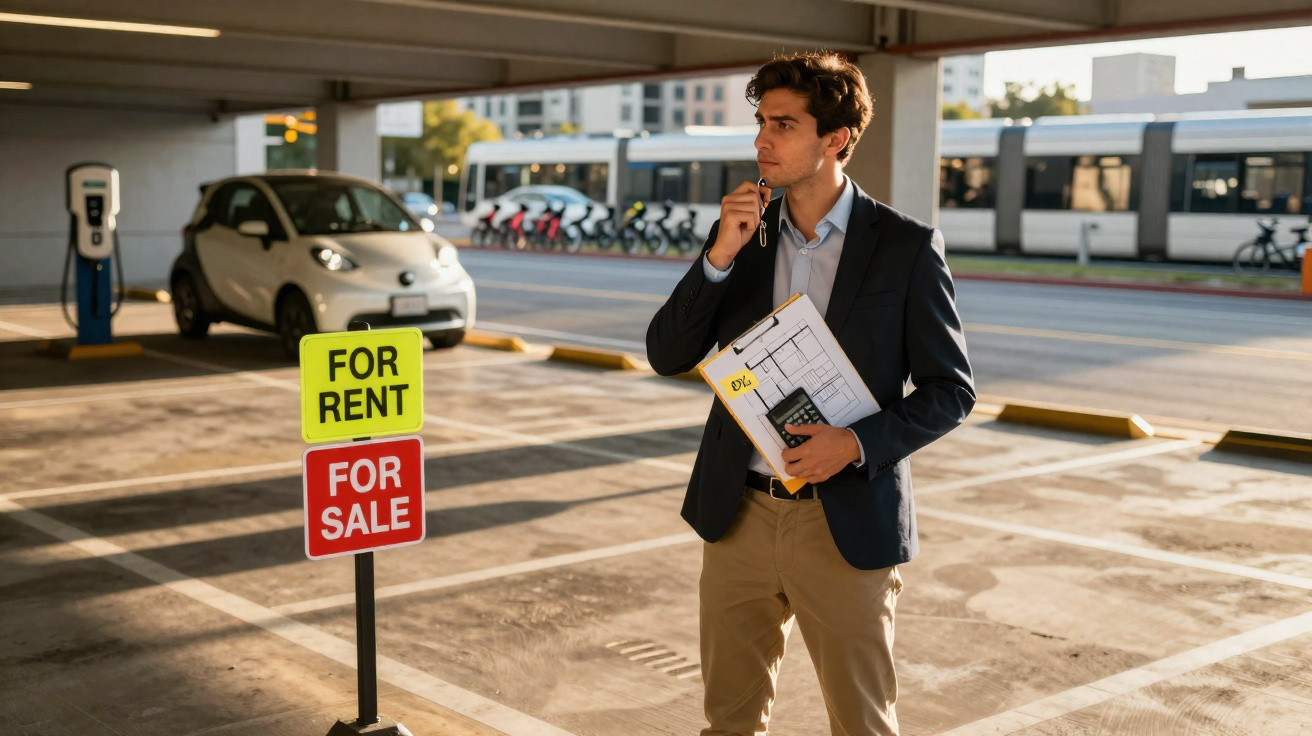
For many smaller investors, a plain concrete bay in an underground garage can now appear simpler to run than a studio flat and more affordable than many financial products. However, beneath the polished promise of “up to 8% yield”, the 2026 parking market carries substantial local risks, complicated rules and an unclear outlook for private car use.
Why parking spaces are attracting investors again in 2026
In many cities, rents have stalled, mortgage criteria have tightened and stock markets seem unsettled. Against that backdrop, parking can look reassuringly straightforward: buy a space, let it to a motorist and receive monthly income. That is the principle, at least.
An affordable entry point for smaller budgets
Unlike a flat or modest house, a parking space does not usually require a six-figure sum. Across many European and US cities, an outdoor bay can cost roughly £5,000–£10,000, while a secure underground space in a high-density location may be priced at around £15,000–£30,000.
- A lower purchase price can reduce, or remove, the need for a mortgage.
- There are generally fewer legal and technical checks before completion.
- Where demand is high, void periods may be shorter.
This relatively modest investment level appeals to first-time investors, employees seeking a second source of income and retirees who want to place some savings in a tangible asset without taking on too much.
Overlooked benefits: limited upkeep and consistent demand
A parking bay has no kitchen, boiler or shower tray that can leak into the property below. Major structural repairs are normally the responsibility of the building owner or car park operator.
Parking appeals because the investor often handles only three tasks: collect rent, pay basic charges, and watch the local market.
There is no tenant inventory, no disagreements over damaged furniture in a partly furnished property and little emotional involvement. In many developments, one occupier remains for years, whether they are a resident, nearby employee or local business owner. This stable pattern of use can provide a welcome feeling of regularity, provided car ownership remains widespread.
The 8% promise: what parking yields actually look like
Sales material often promotes returns of “up to 8%” or more. Such figures are not necessarily unrealistic, but they depend on very particular circumstances: a pronounced gap between demand and supply, strict restrictions on street parking and few unanticipated expenses.
Why location can turn a concrete bay into an investment asset
For parking, the familiar property rule about location is even more unforgiving. Two spaces within the same city can deliver dramatically different results simply because they are a few metres apart.
| Location type | Typical gross yield | Key risk |
|---|---|---|
| Historic city centre | 6–9% | Policy changes, pedestrianisation |
| Dense residential district | 5–7% | New garages in new builds |
| Near major station | 3–6% | Oversupply from public car parks |
| Outer suburbs | 2–5% | Weak demand, easy on-street parking |
Areas where motorists spend 20 minutes driving around in search of a bay can support high monthly rents, particularly when councils increase street-parking charges. Conversely, major rail interchanges may be surrounded by large private operators offering multi-storey parking and steep discounts. In less dense suburbs, residents can often leave their cars on the road without charge.
Moving from brochure yield to genuine net returns
Gross yield measures annual rental income against the purchase price alone. Net yield deducts every expense incurred before the money reaches your account. It is this latter figure that reveals the actual outcome.
- Service charges for the building or car park.
- Council tax, property tax or a comparable local charge.
- Insurance, however limited its scope.
- Occasional management costs where the work is outsourced.
- Tax on rental income and possible social contributions.
In many mature markets, a “7–8%” gross yield on paper turns into 4–6% net once tax and charges bite.
That can still compare favourably with many residential buy-to-let investments, particularly in areas where rent controls apply. Nevertheless, investors who overlook these deductions may be disappointed once they complete their first full tax year.
When selling a parking space becomes difficult
Letting a well-situated parking bay is often relatively quick. The greater pressure normally comes at the end of the investment, when it is time to sell. Parking markets do not usually operate like broad national housing markets; instead, they can be highly specific to a particular building or even a single street.
A buyer market limited to a handful of streets
The number of potential buyers is frequently small. Purchasers may include people living in the building, nearby workers, small investors and, occasionally, local authorities. A newly opened public car park, a supermarket offering free parking or altered traffic flows can transform the market in under a year.
Transaction costs can also have a disproportionate effect. Notary charges, registration taxes and administrative fees absorb a significant share of a small transaction. On a £12,000 space, fees amounting to 10–15% leave little scope for a capital gain, meaning prices may need to rise sharply before you merely break even.
Keeping parking investment exit options available
Those who view parking as a quick flip often underestimate the importance of timing. A patient approach and a defined plan can make a material difference.
When buying a parking space, you already need a story for how, and to whom, you will sell it later.
Useful practical measures include:
- Focus on buildings where there is a waiting list for parking bays.
- Review previous sale prices within the same block or street.
- Ask the building manager about current levels of demand.
- Consider nearby urban schemes that could either reduce or increase demand.
When the time comes to sell, current residents and local shop owners are often the first people to approach. Convenience matters to them, and they may pay a modest premium over a remote investor. Clear information about access arrangements, low charges and additional features, including CCTV or EV charging points, can improve your negotiating position.
Regulation, climate policy and the future of private parking
Parking is not immune from political debate. Cities are reshaping streets around cycling and buses, while national governments encourage electrification. These changes could increase the value of some private bays while making others obsolete.
Regulations that may alter parking profitability
A number of regulatory developments are already appearing in major European and North American cities:
- Obligations to provide EV charging capacity in communal garages.
- More demanding fire and safety requirements for underground car parks.
- Tax reforms aimed at “non-productive” land and vacant spaces.
- Wider low-emission zones that limit use of older vehicles.
Every additional requirement can create new costs for owners, including contributions towards charging infrastructure, higher service charges or compulsory refurbishment works. At the same time, good EV-ready bays in dense neighbourhoods may let more quickly and command higher rents, as drivers seek dependable charging close to home.
Soft mobility, ZEVs and the car’s declining role
Urban transport increasingly combines cycling, e-scooters, better bus services and ride-hailing. Younger people are postponing car ownership or choosing not to own a car at all. In certain cities, the number of vehicle registrations per household declines each year. For investors, this creates an unavoidable long-term question: who will still require private parking in 10–20 years?
Spaces that survive the shift often sit in premium micro-locations where alternatives remain inconvenient, or where cars still represent a core work tool.
Examples include surgeons on call near hospitals, tradespeople transporting tools and suburban residents living at the edge of a rail network. In these situations, secure off-street parking can remain highly attractive, especially where it includes dependable charging, 24/7 access and good lighting.
How to stress-test a parking investment in 2026
Essential checks before committing
A number of practical tests can help distinguish resilient opportunities from fragile investments:
- Street-level assessment: visit during busy periods and count cars looking for bays.
- Sensible pricing: compare local rental listings rather than relying only on sales asking prices.
- Building rules: examine co-ownership rules covering access, subletting and EV use.
- Infrastructure: assess lighting, security gates, water ingress and height restrictions.
- Policy mapping: review local proposals for pedestrianisation or additional public car parks.
A simple spreadsheet can be used to test different outcomes. Start with a cautious rent assumption, allow for two to three months of vacancy over a year, add every known charge and apply a realistic tax rate. Next, model a higher property tax or an increase in service charges. Does the resulting yield still outperform low-risk bonds or a diversified ETF?
Expanding through bundles, specialist tenants and layered risk
Some investors expand this approach by purchasing several bays in the same building or neighbourhood. This can spread vacancy exposure and may support negotiations for a small seller discount. Five spaces let individually may provide steadier cash flow than one bay.
Other owners look for specialist occupiers, such as car-sharing providers, local firms requiring storage or fleets of small electric vehicles. These arrangements can involve longer agreements and greater wear, but may secure income for several years and support tailored upgrades such as marked bays or dedicated chargers.
Parking can also complement other objectives. A resident buying an additional bay to let can offset the running costs of their own space; a business owner may use rental income to cover part of their office expenditure; and a family investor might regard two bays as a flexible capital reserve that can be sold if a larger property opportunity arises.
Risk remains, however. Placing all capital in one building leaves an investor exposed to structural problems or one severe policy change. Where possible, owning spaces across several districts or even different cities can lessen that impact and preserve flexibility as urban mobility continues to evolve.
Comments
No comments yet. Be the first to comment!
Leave a Comment