
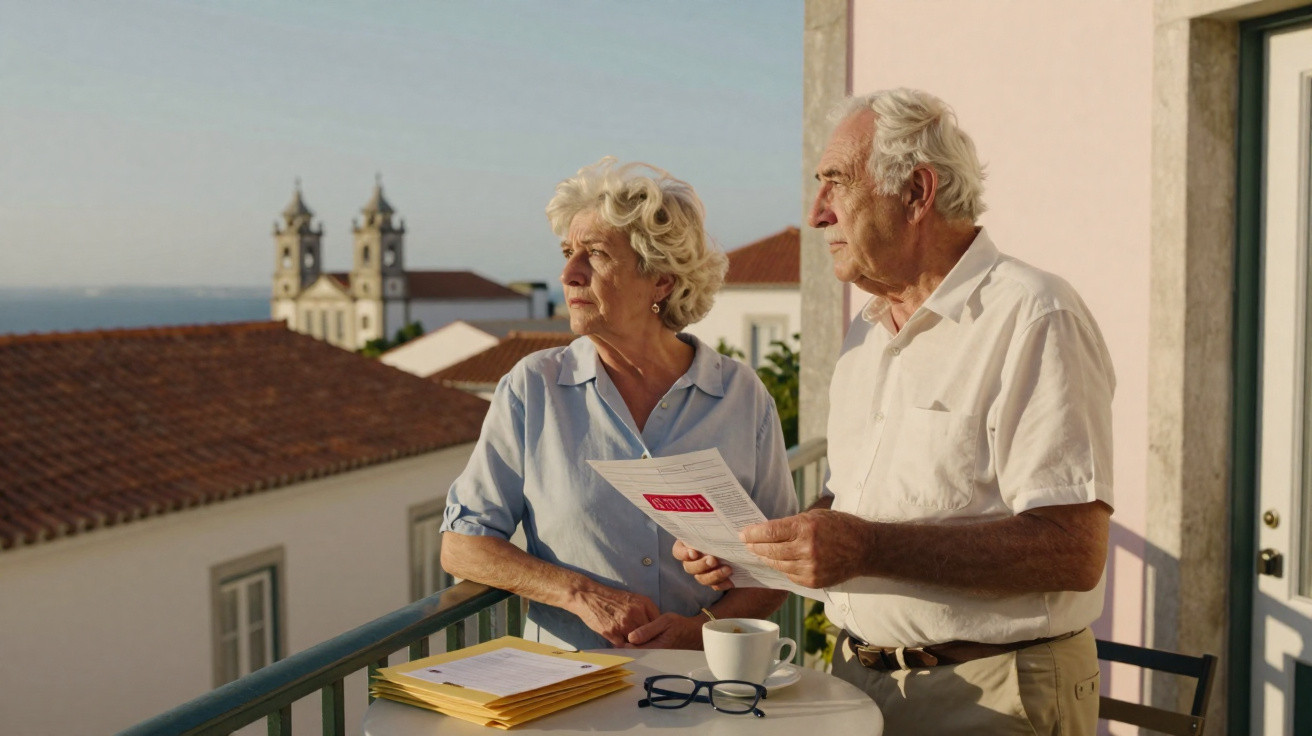
The letter arrived on doormats in peaceful seaside towns and drowsy villages, tucked between supermarket leaflets and charity requests.
It contained a few lines of council terminology, a revised percentage and mention of a “consultation”. But to thousands of retired people with an unassuming second home, it sounded like a warning: “Proposed council tax premium on second properties.” Many gave it a far harsher name: a war on older people. Throughout Britain, pensioners who saved, sacrificed and downsized to buy a modest retreat are now confronting rising bills, public disapproval and a difficult breakfast-table question: can we still afford the life we created?
On a wet Tuesday in February, Margaret and Alan sat in their Kent kitchen, their tea cooling as they read their council’s consultation papers. Both are in their late seventies and own a small Devon flat, purchased twenty years ago when property was cheaper and retirement seemed full of possibility.
At the time, their second home represented a dream: summer stays with the grandchildren, winter visits from friends and somewhere away from the grind of the M25. Today, local meetings describe that very flat as a “luxury asset” which ought to face heavy taxation to help tackle the housing crisis.
Alan traced the suggested charges with his finger: a 100% council tax premium for second homes, perhaps rising to 150% in later years. “We can’t do this forever,” he murmured. A particular silence filled the room: the sort that arrives when strangers appear to be putting a new price on your life. The postman carried on down the street. Inside, a fresh worry began to grow.
When a retirement dream becomes a political target
Local councils across the UK are considering steep council tax increases for second homes, presenting them as a quick answer to squeezed budgets and frustrated local people unable to secure somewhere to live. In principle, the case appears straightforward: charge more for empty or occasional-use properties, raise money for public services and make clear that housing should provide homes rather than store wealth.
In practice, many of these “second homeowners” are older couples who spent decades clearing the mortgages on two small properties, frequently making sacrifices invisible in any spreadsheet. The divide is painfully stark. Residents want action on soaring rents and communities hollowed out by seasonal occupation. Pensioners, meanwhile, receive letters that feel not like policy announcements but like discreet eviction notices from a retirement they believed they had earned.
Look at North Norfolk or areas of Cornwall, where second homes have long been politically contentious. Councils in these places have either agreed, or are considering, 100% council tax premiums on second homes – so a bill could double almost overnight. Public discussion often centres on affluent Londoners with large holiday properties, while the reality locally is far less neat.
Along coastal roads are retired former nurses in very small bungalows, ex-postmen living in inherited terraces and couples who let their property for half the year simply to fund repairs. Plenty are not wealthy in any conventional sense; they are asset-rich but cash-poor, relying chiefly on the state pension and a limited private pension. Calling someone a “greedy landlord” rings hollow when they are counting pennies at the chemist.
There is a hard rationale behind these higher tax bands. Councils are under strain. Social care expenditure continues to rise, central government support has been restricted and each winter brings reports of services under pressure. At least politically, second homes look like easy targets: they are seldom occupied all year and are assumed to belong to people with comfortable finances.
But treating the issue only as an exercise in figures conceals its human consequences. For retired couples currently paying £2,000 annually in council tax, a 100% premium raises the charge to £4,000. For some, that decides whether they heat their home, or whether they can help a grandchild with university rent. Officially, the argument concerns housing supply and fairness. At kitchen tables, it concerns anxiety and bitterness.
How pensioners can quietly fight back and stay afloat
For older owners confronted with substantial second-home tax rises, the most basic survival measure is also the bluntest: establish the precise figures. That means more than approximate calculations over a glass of wine; it requires a clear written account of how the changes affect them each month.
Begin with last year’s council tax bill for the second property. Record its band, the amount paid and any discounts already received. Then apply the premium your council is consulting on – 50%, 100% or another rate – and convert the result into a monthly reduction in pension income. It is not pleasant, but it transforms an indistinct fear into a definite choice.
Once the numbers are clear, possible routes can be considered: letting the property for additional weeks, splitting costs with relatives or converting it into a long-term rental to potentially receive different tax treatment. Without a clear picture, every option feels threatening. With one, you are at least navigating your own course.
Many pensioners who open these letters first feel angry, then guilty, and eventually worn out. Some grew up when saving for a second property was openly encouraged: a secure asset and a reward for years of employment. They are now told that the same conduct is a social problem deserving punishment.
There are practical pitfalls as well. A common error is overlooking an early consultation notice because “they’ll never really do it”. Another is taking major decisions alone late at night, when every outcome appears bleakest. Show the documents to adult children or trusted friends, even if doing so feels awkward.
There is also an unspoken urgency to sell before charges climb still further. That may go badly wrong if you accept a low offer in haste or create capital gains issues you had never anticipated. Let’s be honest: nobody truly reads the small-print tax wording at the bottom of forms every day.
As former teacher Brian, 79, from South Wales, put it after his local authority proposed a second-home premium:
“We didn’t buy a yacht or move money offshore. We bought a tiny place by the sea so the grandkids would always have somewhere to stay. Now I’m being told I’m clogging up the housing market. It feels like the rules changed halfway through the game, and no one bothered to tell us.”
For people attempting to manage this emotionally fraught situation, several practical anchors may help:
- Check whether your second property has ever been treated as your main residence; this history may affect tax.
- Speak to neighbours, who may face the same increases and know of local alternatives.
- Investigate council hardship schemes or discretionary reductions, even if you assume you “don’t qualify”.
- Retain dated copies of every letter and consultation response you submit – documentary records matter.
- If selling is being considered, consult an independent adviser before estate agents and prospective buyers begin shaping the discussion.
A new fault line between generations – and what it says about us
The dispute over second-home tax premiums has revealed a wider tension running through British society. Younger renters, constrained by expensive homes and short tenancies, see lightly used holiday properties and feel intense anger. Older homeowners, by contrast, see their modest havens being turned into emblems of greed.
Some of the wording is subtly savage: “Empty homes tax.” “Crackdown on part-time properties.” “Squeezing out locals.” Anyone with a second home who still watches every pound may experience this as a public campaign of humiliation. The distinctions between those who are genuinely affluent and those simply managing to cope are flattened into headlines and hashtags.
Yet something more complex lies behind the slogans. Councils are right to say that villages left dark for nine months each year are not thriving communities. Young families need homes. Public services must be paid for somehow. The real issue is whether concentrating pressure on pensioners with modest, carefully acquired second homes genuinely addresses the problem, or merely gives politicians an easy narrative.
Most of us recognise the shock of receiving a bill and suddenly seeing our lives judged according to somebody else’s standards. Are you “comfortable”? “Asset-rich”? A “burden” on the system? Such labels spread quickly through policy debates, but seldom match the people to whom they are attached.
Some retirees are already adjusting through quiet, resourceful measures. They share second homes with siblings or cousins to divide council tax costs. They turn a previously private retreat into a part-time let that generates just enough income to cover the additional charges. Others are rethinking the property as a semi-permanent home for a younger relative – a student, or a separated son or daughter seeking a new start – so that it can no longer be described as “empty”.
The emotional price is more difficult to calculate, but remains ever-present. There are worried conversations about “being forced out”; grandparents question whether they must sell the place where their grandchildren learned to swim; and residents feel resentment towards councils that speak of “consultation” when the decision seems already settled. People can live with hard rules more easily than with the sense they’re being quietly blamed.
Some people will sell, take the money and leave the pressure behind. Others will carry the higher bills for as long as possible, cutting back on holidays, presents and modest luxuries that made retirement more than mere endurance. A minority will resist – alone through appeals and letters, or together by forming local groups that plainly insist not every second homeowner is the enemy.
What these proposed taxes ultimately demand is a discussion about responsibility between generations. Did older people “hoard” housing, or did they follow the rules they were given? Do higher premiums offer a fair adjustment, or retrospective punishment? There are no simple answers, only people such as Margaret and Alan, sitting at kitchen tables, calculating with unsteady hands and asking exactly when their dream became a problem to solve.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Rising premiums | Many councils are considering up to a 100% surcharge on council tax for second homes | Understand the true scale of a potential increase to a retirement budget |
| Impact on retirees | Pensioners are often “asset-rich, cash-poor”, made vulnerable when bills suddenly double | Recognise these circumstances and prepare for forthcoming financial strain |
| Available options | Discreet possibilities include partial letting, cost-sharing and checking local reduction schemes | Identify practical ways to avoid a rushed sale or silent distress |
FAQ:
- Are all councils really planning to double tax on second homes? Not all, but many have new powers to charge premiums and a growing number are proposing 50–100% extra on council tax for second properties, especially in tourist hotspots.
- Does this only affect wealthy second-home owners? No. While some owners are very comfortable, a large group are retirees with small flats or cottages, living mostly on pensions and modest savings.
- Can I challenge or appeal a second-home premium? You can’t usually appeal the policy itself, yet you can challenge your property’s tax band, respond to consultations, and ask about discretionary reductions or exemptions.
- Will letting my second home change how I’m taxed? Potentially yes. In some cases, switching to a genuine holiday let or long-term rental can alter the way local charges and national taxes apply, but professional advice is vital.
- Is selling my second home the only realistic option? Not always. Selling is one path, but shared ownership with family, partial letting or restructuring your finances can sometimes keep the property viable under higher tax bills.
Comments
No comments yet. Be the first to comment!
Leave a Comment