
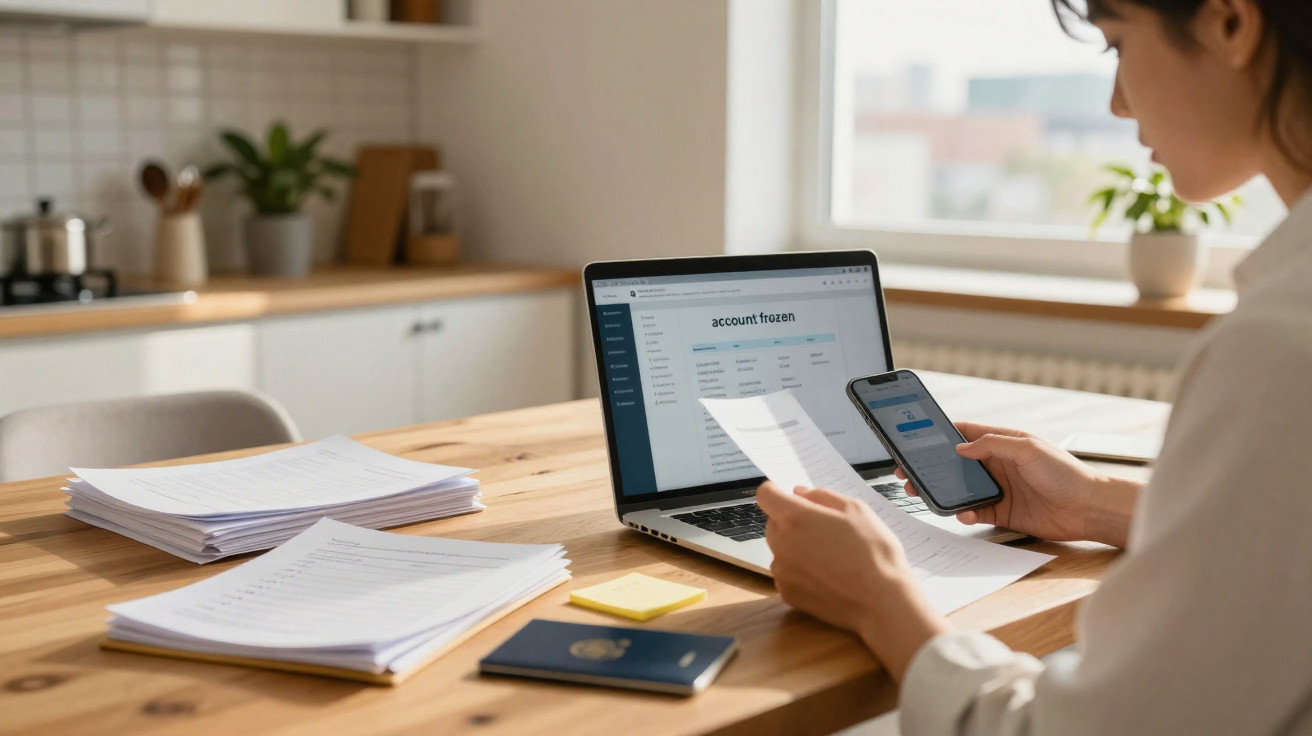
Card declined. Again. Emma checked her balance with a frown, then noticed an alert in her banking app: “For security reasons, your account has been temporarily restricted.” There had been no advance notice and no proper explanation. Her account was locked, and she was standing with a trolley of groceries she could not buy.
She later discovered the cause: an incoming payment from a relative overseas had been marked as “suspicious”. Her bank requested supporting documents: evidence of the money’s origin, proof of its purpose, and, in effect, proof that Emma was not a criminal.
She had not prepared anything. There were no screenshots, payslips or letter from her uncle. There was only a frozen account and an increasingly humiliating situation.
She believed the money was hers.
Then she found out how the system actually operates.
Why your bank can suddenly lock what feels like “your” money
The shock is so severe because most of us see a bank account as a safe bearing our name. You pay money in, it remains there, and you withdraw it whenever you choose. It seems straightforward. When a bank locks that safe at the press of a button, it can feel like a personal betrayal - rather like somebody replacing the lock on your own front door.
Banks view the arrangement very differently. Although the account is in your name, they are legally responsible for the money passing through it. Algorithms and specialist staff monitor every payment in, unusual transfer and large cash deposit for signs of money laundering, fraud or tax evasion. If an activity pattern appears questionable, they are under pressure to intervene before investigating further.
That is how your wages or lifetime savings can appear “suspicious” on an otherwise ordinary Tuesday morning.
Consider Karim, a freelance web developer whose three clients all paid late at the same time. Each payment arrived during the same week, and each was a round figure. For the first time in months, he opened his app to see a reassuring balance. Then he tried to pay his rent, only for the payment to be declined. The bank had stopped outgoing payments “pending verification” of the incoming funds.
When he eventually spoke to someone by telephone, the adviser was almost apologetic. Three sizeable payments from overseas payment processors, after a quiet period on the account, had activated the bank’s anti-money laundering system. He was asked to provide invoices, client email correspondence and even screenshots from his freelance platform account.
Karim possessed the paperwork, but it was spread across an old laptop, two cloud-storage accounts and his email inbox. Gathering it all took four days. During that time, he had money in the bank but was unable to use it.
For a compliance officer, the reasoning can seem brutally logical. Banks face heavy regulatory demands to prevent “dirty money” from entering the financial system. Their automated checks examine deposits for factors including the country of origin, the amount, frequency and abrupt changes in account behaviour. Once the software identifies a risk, freezing or restricting the account is often considered the least risky option.
Your rent and groceries are not their immediate concern. Their focus is on penalties, audits and damaging headlines. This is why they may unexpectedly ask for evidence regarding money that you know is legitimate: payslips, contracts, inheritance letters, sales agreements and, in some instances, WhatsApp screenshots.
The law does not require them to give you prior warning. Instead, it requires them to explain afterwards why they could not simply ignore the warning signs.
How to “future-proof” your deposits before trouble starts
One particularly useful habit is to set up a “money story” folder now, before anything unusual happens. It need not be elaborate. Create a basic digital folder on your phone or in cloud storage, and save every document that may one day explain the source of a payment. This could include employment contracts, freelance invoices, family loan agreements and clearly labelled screenshots of transfer confirmations.
If you are expecting a large payment, leave a short explanation for your future self, such as: “£3,000 – refund from cancelled wedding venue, signed contract attached.” It may feel unnecessarily thorough at the time. But if a bank employee later asks why a month of modest payments was followed by a £20,000 lump sum, that brief note and attached PDF could prove invaluable.
This is not about being afraid of your bank. It is about avoiding the need to search through two years of email chains while your card continues to be declined.
Account freezes are especially difficult when life is already complicated. A bereavement, flat sale, divorce settlement or move overseas can all send money in unexpected directions while emotions are already strained. Yet on a banking screen, the only visible detail may be “large transfer out of nowhere”.
A woman receives an inheritance from her father’s estate on a Monday. Two weeks later, she transfers the same amount to another bank offering a better interest rate. Her original bank identifies this as “layering” - a recognised money-laundering technique - and restricts the account while it investigates. She is still grieving when she first hears the term “source of funds”.
The bank is not trying to be cruel. It is applying rules designed with drug cartels in mind, rather than bereaved people. The frustration lies in the gap between your real circumstances and its risk model. Understanding that gap does not make the experience fair, but it does allow you to prepare rather than assume that “it won’t happen to me”.
“On paper, it’s just numbers moving between IBANs. In reality, it’s someone’s rent, someone’s chemo, someone’s last chance to fix their car and keep their job.”
Several familiar patterns can turn an ordinary customer into a red flag on a bank dashboard. These include large cash deposits into an account with no history of cash use, unexpected international transfers involving high-risk countries, dormant accounts suddenly receiving substantial sums, and multiple third-party payments with unclear references such as “refund” or “loan”.
Let us be honest: hardly anyone does this perfectly every day. Nobody maintains a flawless paper trail or writes completely clear payment references for every transfer. Banks understand that. The aim is not perfection, but reducing uncertainty when a payment is stopped.
Use this straightforward mental checklist to avoid the most difficult situations:
- Before a large deposit, ask yourself: “Could this look unusual from the outside?” Then retain at least one document that explains it.
- For loans between family members, write a brief email or note setting out the amount, reason and repayment arrangements.
- When selling a car or another valuable item, keep the advert, relevant messages and a copy of the signed agreement or receipt.
- For overseas payments, record why the money is arriving from that country and the circumstances behind it.
- Following an account restriction, remain calm, ask exactly which documents are required, and request a written summary by email.
A new way of looking at “your” account
Once you understand that a bank is not simply a personal safe but a gatekeeper to the financial system, the way you view deposits and supporting documents changes. You may still be angry when funds are frozen, but you are less likely to feel completely blindsided. You know the gate may occasionally shut because you understand how its hinges work.
The emotional impact does not vanish. On a difficult day, a blocked card can feel like criticism of your choices, background or country of origin. On a better day, it may seem like overly cautious software doing its awkward best. Between those responses is a quieter reality: once you know the rules, you have more influence than you might think.
Maintaining your own “source of funds” file is one form of that influence. Another is discussing openly with family why and how money is transferred. You can also contact your bank in advance to ask which evidence it prefers for matters such as inheritances, cryptocurrency cash-outs or property sales. Rather than pleading for access to your own funds, you can say, “Here’s the story, here’s the paper, how do we make this smooth?”
Most people have experienced the way financial worry quietly affects the rest of a day, shaping every minor choice. You choose cheaper food, avoid taking a taxi or cancel a drink with a friend. Now add a frozen card and no indication of when it will be resolved. That is when a small amount of dull preparation becomes a powerful act of self-protection.
No magic phrase can guarantee that a bank will never freeze your account. There is no secret form that makes you immune. What you can create is a living record of your financial life that remains in your hands: a set of simple routines that turn future interrogations into short conversations.
Perhaps you will never need it. Perhaps you will, and you will be the only person in the queue whose panic lasts five minutes rather than five days. In either case, when somebody says “the bank can block your account without warning”, you will know that is only half the story.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| An account freeze can happen suddenly | Banking algorithms may restrict an account without warning as soon as a deposit appears unusual. | Recognising that this is common can help you avoid seeing it as a personal attack. |
| “Supporting documents” are crucial | Contracts, invoices, proof of sale and inheritance paperwork can help release funds more quickly. | Provides a practical plan for preparing useful documents in advance. |
| Basic organisation makes a major difference | A simple digital folder containing notes and screenshots can resolve a review more easily. | Reduces stress, delays and the risk of a prolonged account restriction during checks. |
FAQ:
Can my bank really freeze my account without telling me first? Yes. Banks may immediately restrict or freeze accounts where they suspect fraud or money laundering, and provide an explanation later. They face legal pressure to act rapidly whenever a risk is perceived.
What kind of deposits usually trigger extra checks? Large one-off payments, cash deposits that do not match your usual pattern, transfers from abroad and major shifts in normal account activity can all draw attention, particularly where there is no clear account history to explain them.
What documents should I keep for future “source of funds” questions? Keep employment contracts, payslips, invoices, sales agreements, inheritance documents, bank transfer confirmations and any written evidence explaining why the money was paid to you.
How long can a bank keep my account frozen? The length depends on the country and the individual case. It may be only a few hours or may last for weeks, particularly if the bank has submitted a report to the authorities. Supplying clear documents promptly will often speed up the process.
Can I do anything if I feel my bank went too far? You may submit a formal complaint, take the matter to the bank’s ombudsman or an external mediator, and in some areas seek legal advice. A written record of every exchange and document supplied will support your case.
Comments
No comments yet. Be the first to comment!
Leave a Comment