
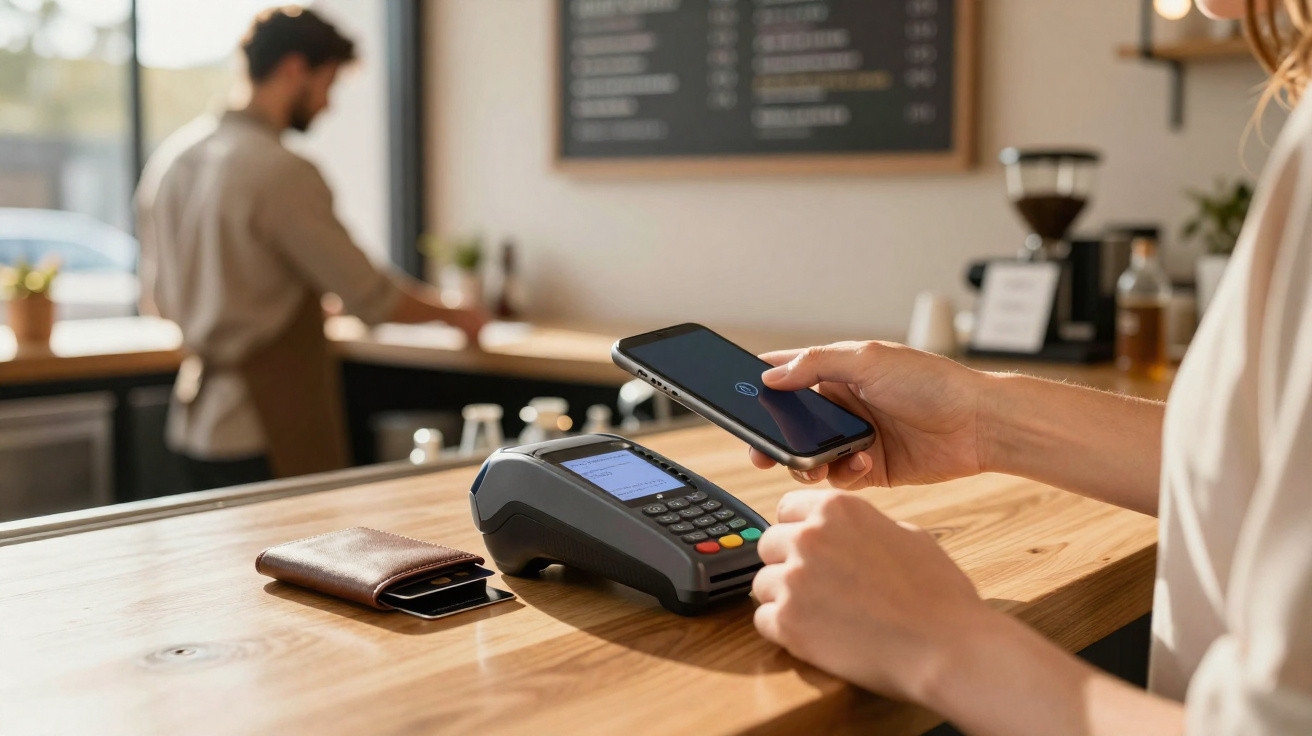
For anyone who simply taps their card on the terminal at the supermarket, pharmacy or petrol station, contactless payment has long been the norm. The UK financial regulator is now changing a key part of the system: the previously fixed maximum for contactless payments may become much more flexible in future - and could theoretically disappear altogether.
What the new rules will change in practice
The latest development follows a rule change by the UK financial regulator, the FCA. From Thursday, banks and payment service providers that can demonstrate robust fraud controls may set their own limits for contactless card payments.
“Rather than a centrally prescribed limit, institutions will be able to set their own maximum amounts in future - or give customers considerably more freedom.”
Until now, the cap for an individual contactless card transaction has been £100. This threshold has been raised several times over recent years, most recently to reflect rising prices and demand for faster payment processes.
The regulator is now going a step further. Instead of stipulating the precise amount, it will set the framework within which banks may operate. The condition is that firms have watertight fraud-prevention systems and communicate clearly with customers.
Will the £100 contactless payment limit disappear immediately?
One common misunderstanding is that the amount at the checkout will automatically change when the new rules take effect. Major UK banks have already said that they will initially retain the current £100 maximum.
Many providers say they are monitoring the situation and will consider making changes at a later date. In everyday terms, nothing will change for consumers for the moment - but the possibility of higher limits now exists in the background.
At the same time, the rules pave the way for more tailored arrangements. Some banks already let customers set their own contactless payment limits, often easily through their banking app.
How banks currently manage contactless payment limits
A look at individual providers shows that the sector already takes widely different approaches. The following examples relate to the UK market, but illustrate how the issue of limits could develop more broadly:
- Major high-street banks such as NatWest, Barclays and Lloyds are retaining the £100 limit, although some allow customers to set lower personal limits in their app.
- Digital banks such as Monzo and Starling have long offered customers the option to choose their own limit or turn off contactless payments.
- Some providers do not allow individual lower limits, but instead offer monthly spending caps for the card as a whole.
They all have one thing in common: changes must be communicated early and clearly. The regulator requires firms to notify customers in good time about every adjustment.
Why the FCA is allowing greater flexibility
The FCA is pursuing several objectives with this move. First, the rules respond to changing consumer habits. In less than a decade, contactless payment has gone from a niche product to the standard method across the UK.
The figures make this clear: according to Barclays data, almost 95 per cent of all eligible in-store card transactions were contactless in 2024. Compared with 2015, monthly contactless payments have increased tenfold. Industry statistics from UK Finance show similarly high proportions for credit and debit cards.
Inflation and rising prices are another factor. As the weekly shop, restaurant meals and visits to clothing shops become more expensive, a rigid limit is reached more quickly. Higher or flexible limits can make paying simpler in these situations.
“The regulator expects the additional flexibility to encourage the industry to invest even more heavily in fraud prevention.”
The reasoning is that providers allowing higher contactless amounts must raise their security standards to avoid carrying substantial costs from fraud cases. Consumers are ultimately intended to benefit from this.
Security: which protections will remain in place
Despite the added flexibility, a central promise remains: customers should continue to be protected where a card is used without authorisation. If a card is lost or stolen, banks must reimburse unauthorised transactions unless the customer has acted with gross negligence.
Technical safeguards also operate alongside this protection. At present, many cards require the PIN to be entered again after a set number of contactless payments or once a defined total value has been reached - the cumulative limit operating in the background.
The new requirements allow institutions to adjust these “cumulative limits” too. This could mean PIN requests are needed less often - or more frequently where a provider wants to place greater emphasis on security.
The role of smartphone wallets and biometrics
Mobile payment methods via a smartphone or smartwatch are a special case. They often already have higher transaction limits because authentication is carried out by fingerprint, facial recognition or the device PIN.
Anyone who mainly pays with Apple Pay, Google Wallet or similar services will barely notice a formal card limit. That is because the device confirms the user’s identity again for every payment.
What does this mean for customers in German-speaking countries?
Although the new rules specifically concern the UK market, banks and payment providers in German-speaking countries are likely to watch closely. Many payment trends reach continental Europe after a certain delay.
Even now, customers at many institutions can manage card features in an app - from disabling particular types of use, such as online payments or overseas transactions, to setting limits on cash withdrawals or card payments.
| Feature | How customers can often manage it |
|---|---|
| Contactless payment | Switch it on or off in the banking app |
| Limit per payment | Set it individually, usually in fixed increments |
| Monthly spending limit | Set a maximum for card payments |
| Overseas use | Allow or block it temporarily |
There are strong indications that banks in these markets will also test more flexible models for contactless limits once regulatory barriers are removed or technical systems are ready.
Practical tips: how users can stay in control
Anyone who pays contactlessly often and is wondering how much freedom makes sense can start with a few straightforward steps:
- Check the banking app: Many apps contain a “card management” or “security” section where limits and features can be changed.
- Take your own sense of security seriously: If high contactless amounts feel uncomfortable, set the limit deliberately low.
- Keep your card in sight: At the checkout too, avoid handing over the card where possible in order to prevent misuse.
- Turn on notifications: Push alerts for every card payment can help identify suspicious transactions quickly.
- Block it immediately if lost: If the card goes missing, it should be blocked straight away via the app, helpline or central card-blocking service.
Why the contactless payment limit is more than just a number
The debate is not solely about the exact amount that can pass across the shop counter without a PIN. It raises more fundamental questions: how much convenience is appropriate? How much control do customers hand over to technology and algorithms? And how are risks shared between the institution and the consumer?
For banks, the limit is a management tool. A higher amount increases convenience, but may also raise the risk of fraud. At the same time, institutions have a strong interest in keeping that risk low, as they bear a large share of the cost when payments are unauthorised.
For consumers, the new flexibility offers the prospect of greater autonomy. Those who actively use their card and app can tailor payment options closely to everyday life - from the traditional plastic card to a fully digital wallet approved with biometrics.
The UK reform therefore shows the direction of travel: away from inflexible universal thresholds and towards dynamic limits that adapt to user behaviour, security technology and price levels. For customers, that means greater convenience, but also greater responsibility to keep track of their own settings.
Comments
No comments yet. Be the first to comment!
Leave a Comment