
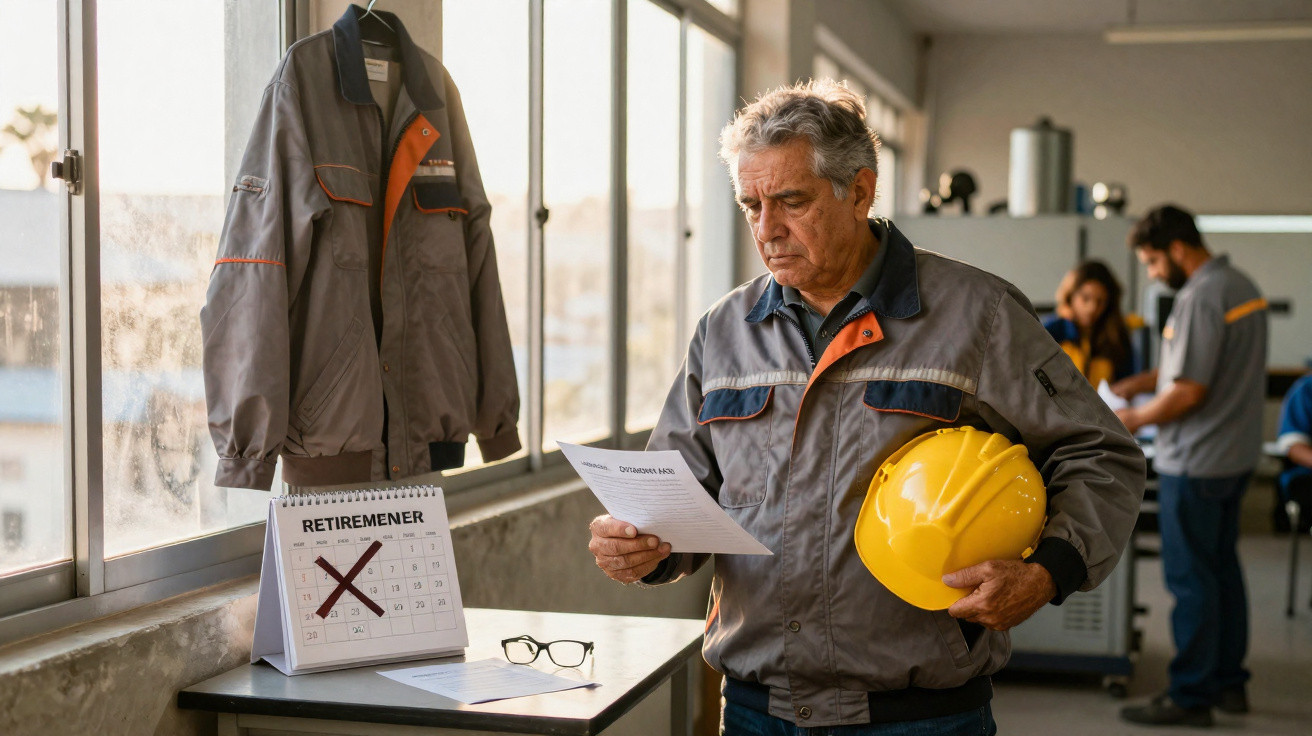
On the 6:12 a.m. train, the evidence is written on people’s faces more clearly than in any statistic. Fingers curl around takeaway coffees, knees still hurt from the previous day’s shift, and people in their sixties look down at the floor as though retirement were a mirage being pushed further along the line. Until fairly recently, many expected to have finished work by now: tending the garden, spending time with grandchildren, perhaps taking on a gentler part-time role.
Instead, they refresh pension calculators on their phones and quietly discuss the newest reform that could “change everything again.”
The central worry is everywhere, even when nobody says it aloud.
Why retirement suddenly feels like a moving target
Go back 20 or 30 years and the picture was straightforward: people worked, kept track of the years and planned around a clearly defined retirement age, usually 60 or 65. They might not have expected wealth, but the finishing point seemed dependable.
Today, that finishing point resembles the speed setting on a treadmill: quietly increased by one notch, then another. Governments lengthen contribution requirements, link the statutory age to “life expectancy” and introduce small provisions that can transform the position of people who began work young or had interrupted careers.
The question is no longer simply “when will I retire?” but “will they move it again before I get there?”
France offers a clear example. In 2023, people protested in the streets when the official retirement age rose from 62 to 64, alongside a requirement for additional contribution years. In the UK, the state pension age is set to reach 67, while debate is already turning to 68 for younger generations. Germany, Italy and Spain follow a similar course beneath technical labels such as “reforms” and “sustainability”.
Ask older shop cashiers, carers or bus drivers what that means, and the response is not economic theory. It is swollen fingers, backs that seize up in the morning and the quiet fear of being too exhausted to continue working while still being too young to stop. They don’t feel “longer life expectancy”; they feel longer shifts.
Officially, people are living longer. In daily life, they are simply working for longer.
The reason behind this is plain rather than mysterious. Ageing populations mean fewer workers support a growing number of pensioners, while public finances come under strain. Governments therefore examine one of the largest items in their budgets - pensions - and consider how to limit the cost. From a spreadsheet perspective, raising the retirement age is the easiest lever to pull.
But a spreadsheet cannot tell the difference between a 66-year-old roofer and a 66-year-old consultant in a heated office. It cannot distinguish decades of night shifts from an office-based career.
That divide between budget calculations and human bodies is where the anxiety grows.
How to react when retirement goalposts keep moving
Denial is often the first response: “I’ll think about it closer to the time.” That reaction is understandable. Pensions can seem distant until you reach 58, when every headline about reform suddenly feels personal. A more protective approach is to start building your own safety net early, even if it initially feels limited.
Well before 60, this means keeping an eye on three basic points: the number of contribution years you are likely to build up, your minimum statutory pension age according to your year of birth, and any other income sources that may be available. Modest savings on the side, even if irregular or imperfect, can make a meaningful difference if the official age is raised again.
You do not need to turn into a financial expert. What matters is having an outline rather than a blank page.
One of the harshest mistakes is believing “they wouldn’t dare raise it again.” The same thing was said when the age increased from 60 to 62, from 62 to 64 and from 65 to 67. Policy changes gradually, but it rarely reverses. That is not a reason to panic; it is a reason not to build your future around yesterday’s rules.
The emotional impact is genuine. Telling a warehouse worker in their late fifties, already physically worn down, that the finishing point is another two years away is hard. This is why conversations at home matter, with partners, adult children and siblings. Discuss plausible outcomes rather than hopes alone.
Most of us know that moment of realising the system was not designed around our individual story.
“Retirement used to be a promise,” a 63‑year‑old nurse in Madrid told me. “Now it feels like a negotiation, and I don’t have the strongest hand.” Her voice wasn’t angry. Just tired. She started working at 18, raised two children, survived night shifts and pandemics. When the legal age shifted, she didn’t see a policy; she saw more winter mornings in the hospital corridor.
Let’s be honest: nobody really reads every reform document line by line every single year.
- Ask direct, simple questions when new rules are announced: “What’s the new legal age for my birth year? How many contribution years do I need?” Remove the jargon.
- Draw up a simple timeline of your working life, including your start date, career breaks and periods of part-time work. Gaps now can create delays later.
- Treat your health as part of your pension - because it is. If reforms extend working lives again, an extra year of physical ability may matter more than an extra year of savings.
- Speak to employers early about possible “exit ramps”: phased retirement, reduced hours or adjusted roles in later working years.
- Recognise that you may need a Plan B. This is not cynicism, but self-protection within a system that keeps changing beneath your feet.
The deeper question nobody wants to answer clearly
Behind the figures and legislation lies a more troubling issue: what is owed to people who have already devoted 40 or 50 years of their lives to work? For a delivery driver with damaged knees at 64, talk of “living longer” can sound like a trick. Those added years mostly exist at the end of spreadsheets, not in their body.
Countries try different approaches, including exemptions for “long careers”, hardship rules and partial retirement. However, these measures are often narrow, bureaucratic and difficult to access. Some people make it through the gaps; others fall straight into them.
The unspoken fear among exhausted older workers is not only “will they delay retirement again?” It is “will anyone care if they do?”
| Key point | Detail | Value for the reader |
|---|---|---|
| Rising legal retirement ages | Many countries now connect pension age to life expectancy and pressure on public budgets | Helps you prepare for probable changes rather than being caught unaware |
| Gap between policy and reality | Physically demanding roles wear workers down faster than office jobs, but on paper they receive the same treatment | Encourages you to push for exemptions or adjusted routes if you work in a demanding role |
| Personal planning as self-defence | Monitoring contribution years, health and alternative income sources | Gives you some influence when governments quietly shift the goalposts |
FAQ:
- Question 1: Are governments really going to delay retirement again for today’s workers? Many already have, and most long-term forecasts point in the same direction: later statutory ages and longer contribution periods. This does not mean dramatic changes every year, but gradual increases are highly likely.
- Question 2: Does higher life expectancy automatically justify working longer? Not necessarily. Average figures conceal major differences between social groups and types of work. White-collar professionals often live longer and remain fit for longer than manual workers. Applying the same rules to both raises fairness concerns that are only beginning to be addressed.
- Question 3: What can overworked seniors do if they physically can’t keep going? Look into early-retirement routes for long careers, disability or hardship schemes, and negotiated departures or lighter duties at work. The rules are complicated, so advice from unions, pension funds or independent advisers can make a substantial difference.
- Question 4: Is private saving really a solution if my salary barely covers my bills? It is difficult, and sometimes not possible. Even small and irregular amounts may help, but the underlying problem is political: how societies choose to share the cost of ageing. Your circumstances are not a personal failure; they form part of a wider structural problem.
- Question 5: How can I stay informed without drowning in technical jargon? Follow one or two dependable sources that explain reforms in plain language, such as trusted newspapers, unions or pension agencies. Seek out simple resources including simulators, explanatory charts and Q&A pages. You do not need every detail, only the few rules that genuinely affect your life.
Comments
No comments yet. Be the first to comment!
Leave a Comment