
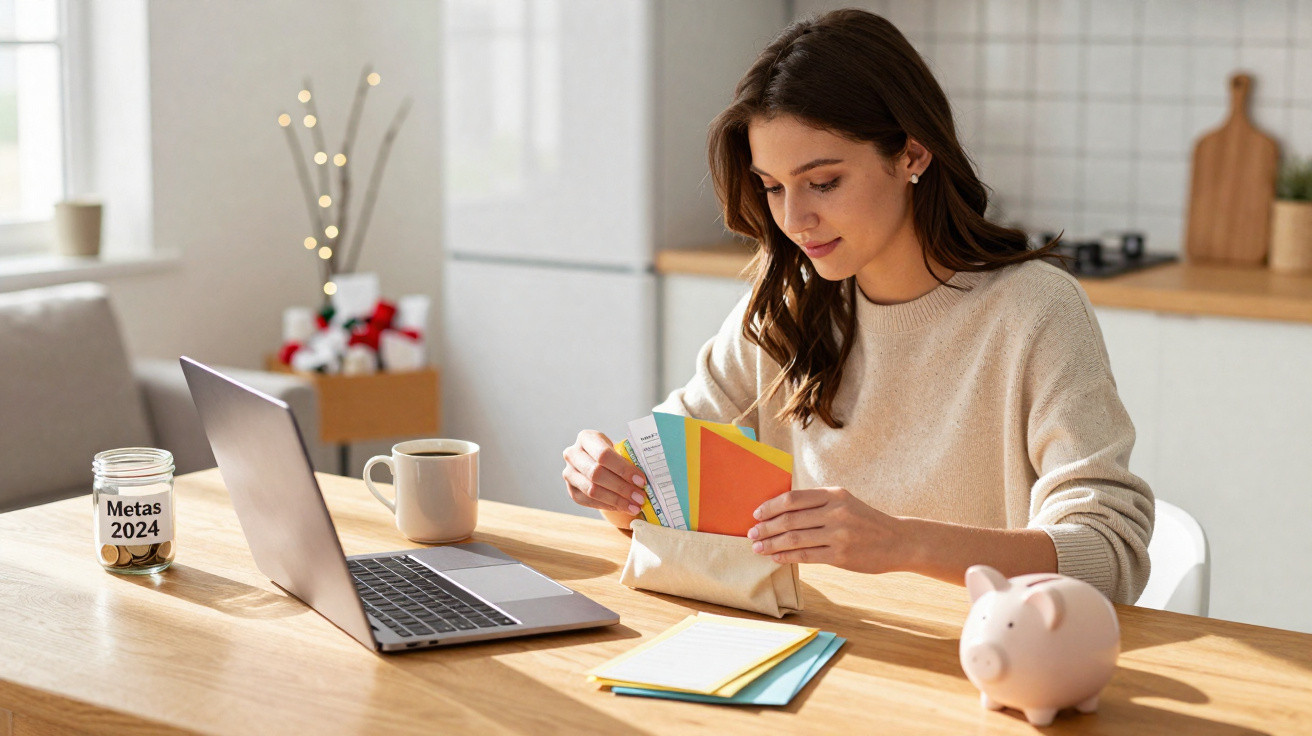
A forgotten bauble sits beneath the sofa, while the pine scent from a tree that should have gone three days ago still fills the room. Unopened envelopes are piled on the table. Beyond the window, life on the street has returned to normal. On the inside, however, the banking app is lit up in an unforgiving red.
Sam flicks through December’s transactions, caught between the usual guilt and denial. There are the extra presents, the “we deserve it” meals out and the last-minute train fares. Rent is nearly due, the card statement is on its way, and that small inner voice is almost audible: “You did it again.”
On a dull afternoon in early January, millions of people are at their kitchen tables making the same calculations in their heads. Some panic, while others put it off. A smaller number take an entirely different route.
They press reset - and quietly alter the course of the year ahead.
The quiet after the festive rush
The period after the holidays has an odd stillness. Parties end, group chats become quieter and your phone no longer pings with discount codes every few minutes. Yet your finances are still reverberating from December, like a hangover that refuses to lift.
That is when a modest financial reset can achieve more than an elaborate “new year, new me” programme. It does not require a complete spreadsheet overhaul or a 90-day challenge. All it takes is a brief, truthful review of your figures, habits and stress triggers.
People who do this do not necessarily appear wealthier. They still buy coffee, forget their loyalty cards and feel tempted by discounted flights. The difference is less obvious. It is there when they open their banking app without tensing up. It is there when their car insurance renews automatically and they do not spiral.
They have replaced guesswork with certainty, and that alone can ease money anxiety for months.
Take Jade, 34, for example. January used to frighten her more than any other month. Working in retail meant lengthy December shifts alongside an even longer present-buying list. By the second week of January, she would ignore post because she knew a credit card statement was buried somewhere in the stack.
After one Sunday ruined by tears over bank charges, she chose another approach. She made herself a promise: one afternoon, headphones on, no judgement. She copied every December transaction into a simple note on her phone, then made three columns: “worth it”, “meh”, “never again”.
Nothing miraculous took place that day. Her balance did not fall and the interest did not disappear. What changed was her shame. She could finally see where the money had gone, and which purchases had truly improved the holidays. That short reset became a private ritual.
By the next Christmas, she owed less money, but, more importantly, she could predict it. The real benefit? She no longer woke at 3 a.m. wondering which bill she had missed.
A “small reset” may look minor, but it is quietly doing several important things. It interrupts the pattern in which December chaos becomes January avoidance, before turning into vague money stress that lasts all year. Rather than allowing the numbers to simply “be what they are”, you give them a boundary.
Psychologists refer to “cognitive load” - the mental burden created by unresolved decisions and problems we half-ignore. Money occupies that space without paying rent: unexplained direct debits, subscriptions you plan to cancel later and the unspoken worry that something vital has been overlooked. A short, intentional reset lightens that burden.
Once you have faced the damage, your mind begins to settle. Instead of existing in a fog of anxiety, you can act on facts. It is also when small, achievable adjustments become realistic. Not “I will never order takeaway again”, but “I’ll protect £40 a month so December doesn’t eat me alive next time”.
The five-step post-holiday reset that lasts
The post-holiday reset that prevents year-long money stress is remarkably quick. It should take one coffee, rather than a whole weekend spent with spreadsheets. Treat it as a debrief, not a prosecution.
First, open your main bank or credit card statement for December and early January. Second, scan it rather than fixating on every detail. Mark the spending that makes you wince, along with anything that truly made you happy. Third, write three plain sentences: what went well, what hurt and how you would like to feel next year.
Next comes the understated but powerful step. Set one straightforward automatic rule that your future self cannot overlook: a standing order into a “holiday + chaos” pot, even if it is just £15 or £20 each month. The amount is not the point. The point is directing your money before December directs it for you.
Most people stumble not because they are bad with money, but because they attempt to repair a year of spending with one dramatic act. They give up meals out, cancel all subscriptions, install three budgeting apps and have burned out by February. Let’s be honest: nobody really does that every day.
This small reset succeeds because it is made for real people rather than financial robots. You do not need to categorise every payment forever, and you do not have to monitor every last penny. You only need a clear snapshot of what has just happened while it is fresh, plus one or two controls you can genuinely use.
The greatest error is immediately choosing punishment. No-spend months, lists of guilt and rules powered by shame may seem disciplined, but they seldom endure. Money stress does not lessen when you attack yourself. It reduces when you have a clear, compassionate plan that your tired January mind can follow automatically.
“My whole year changed the day I stopped asking ‘How could I be so stupid?’ and started asking ‘What pattern is hiding in these numbers?’”
That move from self-blame to curiosity provides the emotional force behind a reset. It is the difference between shutting your banking app with a knot in your chest and closing it thinking, Okay. This is fixable. Practically speaking, a brief checklist can steady you when motivation is low and your to-do list is overwhelming.
- Review last month’s total outgoings and circle the three you regret most.
- Name three purchases that genuinely improved the holidays or reduced your stress.
- This week, cancel or downgrade one thing your future self will not miss.
- Open or rename one savings pot solely for “next December + surprises”.
- Write one sentence about how you want money to feel next January.
A post-holiday reset that continues throughout the year
What stands out about people who complete this small post-holiday reset is not that they become saints of frugality overnight. They still forget reusable bags, agree to weekends away and buy rounds at the pub. The difference is that their financial story for the year has some shape, rather than being no more than a vague wish.
They begin the year having already looked honestly at themselves. They understand which “treats” created stress and which costs were genuine investments in connection or peace of mind. That insight guides low-key decisions throughout the year: bringing a packed lunch twice a week, declining a third streaming subscription or transferring a bonus into the holiday pot before it disappears.
At a deeper level, the reset gives people permission to reconsider what a “good holiday season” means. When you see in black and white that expensive last-minute presents added little joy, while a cheap train fare to visit your sister mattered greatly, your priorities begin to change almost effortlessly. On a calm spring evening while checking your banking app, you will still sense the effect of that January afternoon.
You may transfer £20 into the “December” pot without dwelling on it. You may remove a shopping app instead of scrolling through it out of boredom. They are small choices, prompted by the moment you decided to view your money clearly rather than fear it. On an ordinary Tuesday in August, that is what financial peace really looks like.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Post-holiday “money debrief” | Spend 30–45 minutes reviewing December/January transactions with curiosity rather than blame | Turns vague anxiety into practical insight and reduces mental clutter |
| One small automatic rule | Set up a modest monthly transfer to a dedicated “holidays + surprises” fund | Creates a buffer for next year without depending on willpower or memory |
| Move from guilt to patterns | Identify habits and emotional triggers instead of criticising yourself | Makes lasting change more likely and protects your mood throughout the year |
FAQ:
- How much should I put into a “holiday reset” savings pot each month? Begin with an amount so small that you barely notice it - even £10 or £15. If it does not put pressure on your budget, you can raise it later.
- What if looking at my bank statements makes me panic? Set a 10-minute timer, keep a friend or partner nearby, and use that first session only to notice what is there, not to fix it.
- Do I need a budgeting app for this reset to work? No. A bank statement, a notebook or notes app, and a quiet half-hour are sufficient to spot patterns and establish one small rule.
- How often should I repeat this reset during the year? Doing it once after the holidays is already powerful; a shorter repeat every three months can prevent stress from building up again.
- Can a small reset really make a difference if I already have debt? Yes, because it shows you what is contributing to the debt and prevents fresh stress piling onto the existing problem, which is how people gradually turn things around.
Comments
No comments yet. Be the first to comment!
Leave a Comment