
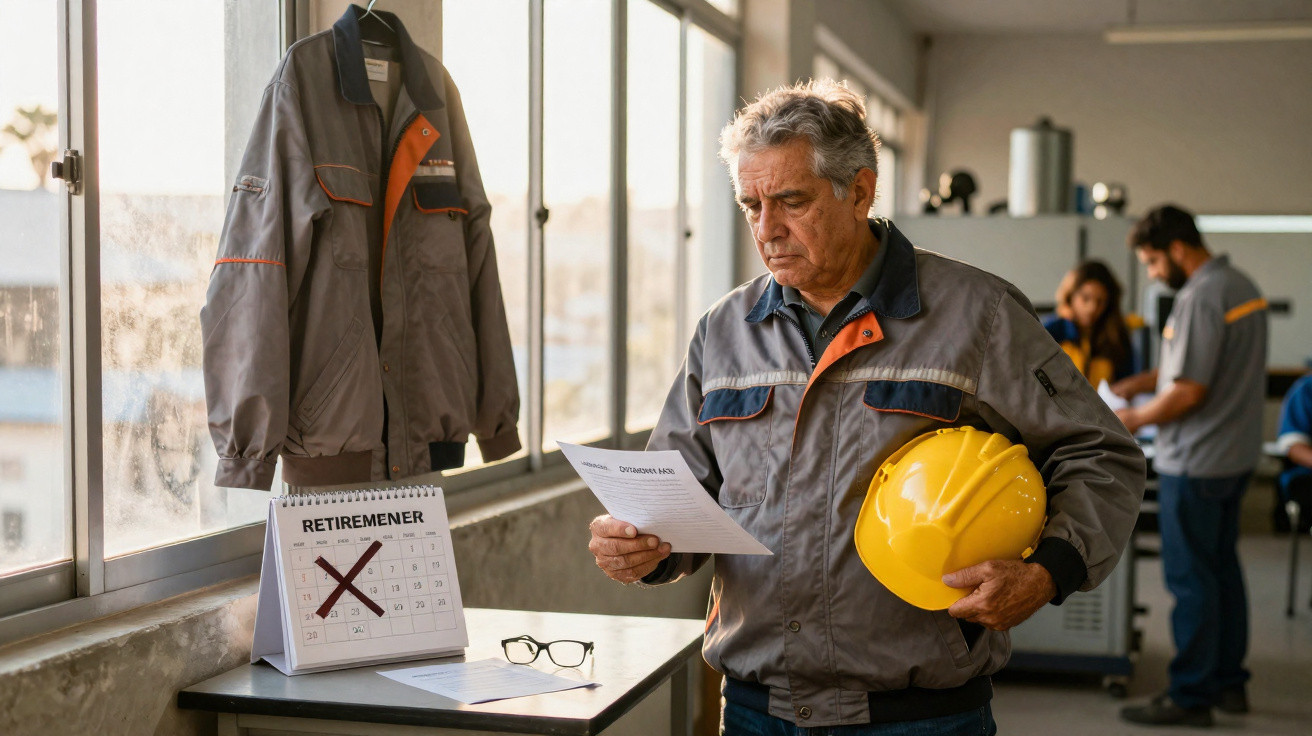
The coffee machine in the office kitchen had only just stopped working when Claire announced that she was leaving for good. At 55, she stood holding a box of plants, wearing an uneasy smile. Her colleagues applauded: some enviously, others with the strained expression that says, “I wish that were me, but I’m not ready.” She spoke about unhurried mornings, yoga, and perhaps some consulting “if I get bored.” Someone had placed a card on her desk saying: “Enjoy the best years of your life.”
What that card did not say is what economists are increasingly prepared to state plainly: those supposedly “best years” can steadily destroy your finances. It is a crash in slow motion.
You may not realise it until the runway has disappeared.
Why leaving work at 55 is not the dream you think
Early retirement can feel like freedom, until you calculate how many years must be financed without a pay packet. If you leave work at 55, you could be supporting yourself for 30 or even 35 years without a regular salary. That is longer than many people spend in employment to begin with. The calculation is unforgiving, however gentle and sunny the fantasy may appear.
Economists highlight something many of us would rather overlook. Retiring at 65 and reaching 90 requires funding 25 years. Retiring at 55 and living until 90 requires funding 35 years. That is 40% more retirement to finance. The dream is not merely longer; it is substantially more costly.
Consider Mark, a project manager who left a major telecommunications company at 56. He had roughly $600,000 in savings and had paid off his home. His friends described him as “set for life.” He felt that withdrawing about $35,000 annually was sensible, with plans to supplement it later through a modest pension and state benefits. Initially, it was wonderful: travelling, renovating the house, and spoiling the grandchildren.
Then inflation proved far worse than his spreadsheets had allowed for. Food shopping, energy costs and insurance all rose gradually. At precisely the point when he was withdrawing the most, his investments fell during a market shock. In ten years, his portfolio had dropped to under half its original value. The anxiety first arrived at 3 a.m., as he lay awake wondering whether he would have to work again at 67.
Economists refer to this combination as “longevity risk” and “sequence-of-returns risk”, yet behind the terminology is an uncomfortable truth. Retire early and every poor market year has a greater impact, because you are taking money from savings while their value is declining. There are no remaining decades of salary to even things out. There is also the discreet threat posed by a long life: the genuine prospect of reaching 85 or 90, healthy enough to live but without enough money to live well.
The simple reality is that early retirement turns minor financial errors into consequences that can alter your life.
How to avoid turning early retirement into a 30-year problem
If leaving work at 55 is a serious aim, you need an approach that appears almost dull on paper. Begin by working out your “worst-case lifespan” figure rather than using your “average life expectancy”. In practical terms, that means preparing as though you will live to at least 95. Next, take the amount you expect to spend each year, increase it to account for future healthcare and rising living costs, and calculate backwards from that point.
A number of economists and financial planners argue that the safe withdrawal rate for people retiring early may be nearer 3% of invested assets than the widely cited 4%. Therefore, if you want $40,000 a year from your portfolio, you may need investments closer to $1.3–$1.5 million, rather than $1 million. It may sound severe, but it marks the difference between “this should be fine” and “this will probably last.”
Many people make the mistake of retiring on a feeling rather than on figures. A sizeable redundancy payment, a soaring share market or an inheritance can briefly create the impression of plenty. Then comes the new car, an expensive holiday or a kitchen renovation, justified by the thought that “we’ve earned it.” Most of us recognise that point at which spending seems like a reward rather than a danger.
This is where economic theory meets ordinary life. The charts will show that excessive spending during the first five retirement years can undermine the final fifteen. You are putting the enjoyment first and postponing the fear. In truth, hardly anyone sits down every day to record each expense and model 30-year outcomes, but those who manage early retirement most successfully do something similar on a regular basis.
Eventually, it becomes less a question of spreadsheets than of identity. Plenty of early retirees discover that work provided more than income: it also supplied routine, friendships and purpose. Replacing these things requires money, time and emotional effort. An economist I interviewed in London put it this way:
“Leaving at 55 rarely ruins people financially overnight. It ruins them slowly, by extending their retirement far beyond what their assets were built to handle, while they underestimate both their spending and their lifespan.”
To safeguard yourself, you need a “life portfolio” as well as a financial one:
- Several income streams instead of one pot of money to draw down
- Defined “spending floors” and limits for “fun money”
- A route into part-time work or consulting through your 50s and 60s
- Affordable housing secured before retirement
- Healthcare and long-term care plans rather than blind optimism
Rethinking what “retirement” at 55 really means
When economists say early retirement can become a financial disaster, they are not criticising the wish for greater control over your time. What they challenge is the traditional idea of retirement: working one day and stopping permanently the next. Many quietly favour another approach: scaling down instead of vanishing. Fewer hours and less pressure, while retaining some income and structure through the riskier period between 55 and 70.
Under this model, retiring at 55 does not mean “never work again.” It means stepping off the career treadmill and creating a low-stress, low-income phase that allows savings to go much further. A part-time job paying $20,000 a year can affect your portfolio as much as adding hundreds of thousands of dollars at the outset, because you are not depleting it as quickly.
This reframing can also lessen the emotional jolt. Rather than moving from a full diary to emptiness overnight, you shift from too much to enough. Endless meetings become selected projects. A single fixed identity becomes a combination of roles: mentor, volunteer, freelancer, grandparent and learner. Questions of money and meaning then take their place at the same table.
Once the celebration of the leaving party has faded, many people privately acknowledge that they did not want to “stop working” at 55; they wanted to stop working in that particular way. The figures support this: combining paid activity with partial drawdown frequently outperforms the “all or nothing” approach by a considerable margin over 30 years. The risk remains, but it becomes manageable.
The central difficulty may demand courage rather than calculation. Courage to examine your finances honestly. Courage to reject an attractive early-exit package that does not quite work on the numbers. Courage to create a slower, less conventional and more adaptable second half of life, rather than copying the glossy postcard image of retirement created for a world in which people died at 72, not 92.
| Key point | Detail | Value for the reader |
|---|---|---|
| A longer retirement costs more | Leaving work at 55 may require you to fund 30–35 years without a salary | Helps you understand why your savings target needs to be far higher than expected |
| Spending in the early years matters | Large withdrawals and lifestyle improvements over the first 5–10 years can deplete your portfolio | Identifies where habits may need tightening so later comfort is not sacrificed |
| Redefining retirement improves security | Part-time work or phased retirement from 55 to 70 eases pressure on savings | Offers a practical route to earlier freedom without risking long-term financial ruin |
FAQ:
- Question 1 Is retiring at 55 always a bad financial idea?
- Answer 1 No. It can be viable with exceptionally strong savings, realistic spending plans and flexibility to earn income later on. The risk is greatest for those who underestimate both their lifespan and their future spending.
- Question 2 How much money do I need to retire at 55?
- Answer 2 There is no universal figure, but many economists recommend planning around a withdrawal rate nearer 3% per year. If you require $45,000 annually from investments, you may aim for roughly $1.5 million in invested assets, adjusted for your location and lifestyle.
- Question 3 What is the biggest mistake early retirees make?
- Answer 3 Spending too heavily during the first decade. Major holidays, home improvements and supporting adult children all at once can speed up portfolio depletion, particularly when markets are weak at the same time.
- Question 4 Can part-time work really change the picture?
- Answer 4 Yes. Even a modest income, such as $15,000–$25,000 a year for several years, can greatly reduce the speed at which savings are drawn down and reduce the chance of running out of money in your 80s or 90s.
- Question 5 What should I do before accepting an early retirement offer?
- Answer 5 Set out your projected spending, test it over a 30–40 year period, include healthcare and inflation, and model scenarios in which markets perform poorly. If the figures work only in a “perfect” world, think carefully before leaving with the farewell balloons.
Comments
No comments yet. Be the first to comment!
Leave a Comment