
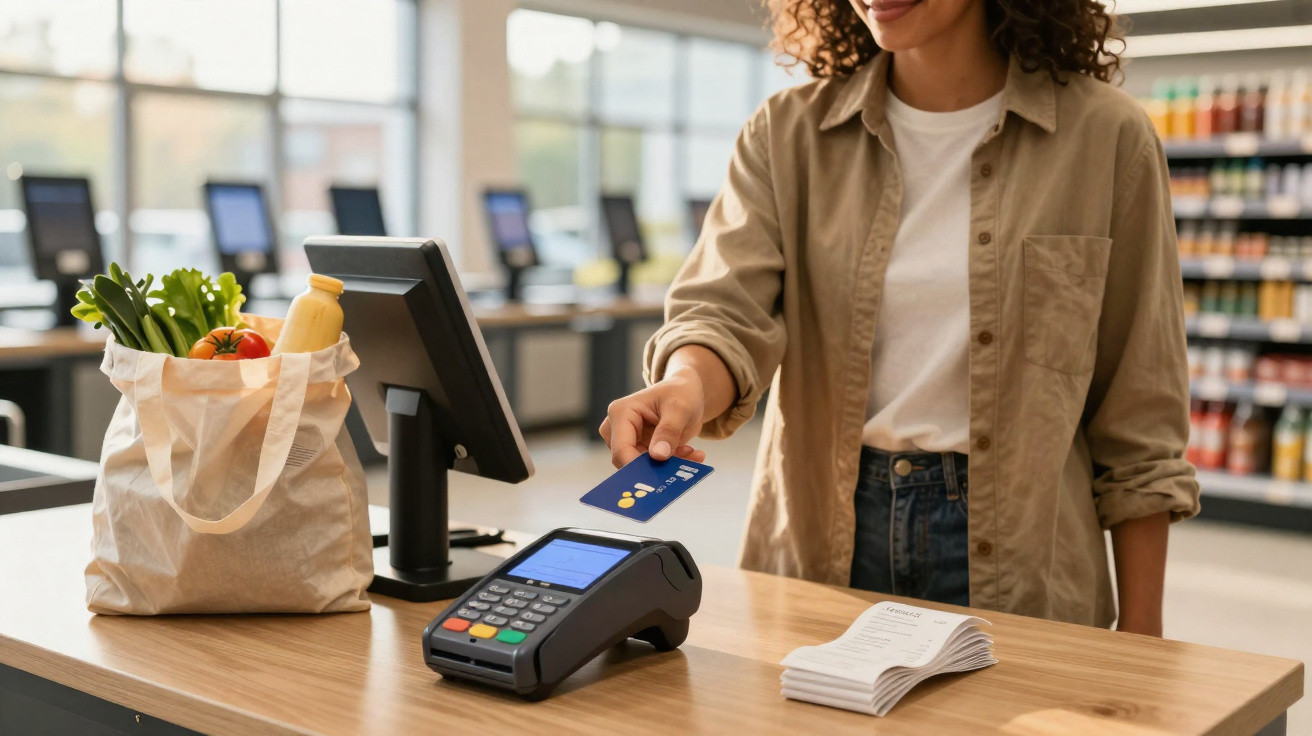
From this week, banks have new authority over tap-and-go payments, prompting fresh debate about convenience, fraud and who determines the rules.
Contactless payments in Britain are set for another change, although this is not simply another rise in the spending limit. Rules taking effect on Thursday will give banks and payment providers far greater discretion over whether contactless card limits are set higher or lower.
What changes from Thursday?
Currently, the standard UK contactless card limit for payments in shops is £100. The ceiling was introduced in 2021, following several increases from the original £10 limit when contactless payments first arrived.
From Thursday, changes to Financial Conduct Authority (FCA) rules will allow banks and card providers with robust fraud safeguards to choose their own contactless limits in future, including limits above £100.
The FCA has removed the rigid national ceiling, giving firms the flexibility to move limits up, down, or even remove them, if they can show they can keep fraud in check.
Importantly, this does not mean that your card will immediately permit £300 tap-and-go purchases. The largest banks in Britain have all said they will retain the £100 ceiling for now, although many already allow customers to select a lower individual limit.
Why the FCA is relaxing the rules
The regulator’s move forms part of a broader package of roughly 50 measures intended to encourage economic growth and bring the financial system up to date. It is designed to help payment companies respond faster to:
- higher prices and inflation, which increase the value of everyday purchases
- evolving consumer behaviour, as people use tap-and-go for almost everything
- emerging technology, including improved fraud analytics and biometric verification
Giving banks scope to customise limits is also intended by the FCA to encourage greater investment in fraud prevention. Firms seeking the benefits of higher limits and increased contactless use will need to demonstrate that customers can be protected.
The regulator’s bet is that flexibility on limits will act as a reward for firms that build tougher fraud defences, not a free pass to take more risk.
How common are contactless payments now?
In under a decade, tap-and-go has gone from being a novelty to the standard choice. Barclays says contactless payments now represent 94.6% of eligible in-store card transactions made by its customers. Each month, people make around ten times more contactless payments than they did in 2015.
UK Finance, the industry body, says that by late 2025 contactless accounted for 67% of all credit card transactions and 76% of debit card transactions. Even with a £100 ceiling, it is still mainly used for lower-value everyday spending: the average contactless transaction is just below £18.
Peter Harmston, head of payments consulting at KPMG UK, calls contactless “the nation’s default way to pay” and anticipates a gradual transition rather than an immediate leap when the new framework begins. He expects banks may lift limits, or remove them altogether for certain customers, during the next few years, provided security remains robust.
What protections will remain?
The liability rules for fraud are unchanged. If your card is lost or stolen and another person makes contactless transactions without your authorisation, your bank must still refund you, provided you have not behaved fraudulently or with gross negligence.
In addition, many cards and payment terminals already apply a background “cumulative” limit. Following a set number of taps, or after a specified total spend, you must enter your PIN to confirm that you remain the genuine cardholder. The FCA’s reforms also allow firms greater flexibility to alter these cumulative controls should they wish.
Higher-value mobile wallet payments through services including Apple Pay and Google Pay remain distinct. These services can already be used above £100 because a phone or watch confirms your identity through biometrics, such as facial recognition or a fingerprint, providing an extra security layer.
How banks are approaching contactless limits
For the moment, the major providers are indicating that little will change. Most will keep the £100 ceiling while offering customers an expanding range of options to manage their own level of risk.
| Provider | Current position on £100 limit | Can customers reduce or disable contactless in the app? |
|---|---|---|
| NatWest | No plans for an immediate change | Yes – customers can disable it and choose a lower limit below £100 |
| Santander UK | Retaining £100, with the position under review | Yes – customers can switch it off or set their own limit in £5 increments |
| Lloyds / Halifax / Bank of Scotland | No changes currently planned | Yes – limits can be selected in £5 steps up to £100 |
| Barclays | Remaining at £100 | Yes – customers can choose their own limit up to £100 |
| HSBC UK / First Direct | The limit stays at £100 | No – lower in-app contactless limits are not currently available |
| Nationwide Building Society | No immediate intention to increase it | Yes – customers can set limits below £100 in the app |
| TSB | Retaining the £100 cap | Yes – customers can lower the limit or disable contactless |
| Starling Bank | Changes are being considered, but no decision has been made | Yes – a slider allows a limit from £100 down to £0 |
| Monzo | Reviews the position regularly; no current change | Yes – customers can reduce the limit or switch contactless off |
| Revolut | No current plan to increase it | The £100 contactless cap cannot be lowered, but overall monthly spending limits can be set |
What it means for everyday shoppers
Over the short term, most people are unlikely to see any change when tapping a card at the supermarket or on public transport. The main limit will stay at £100 at the major banks, while mobile wallet payments will continue much as before.
The more significant change sits behind the scenes. Banks now have permission to test different approaches: they may raise limits for selected groups of customers, create tiered limits linked to account type, or encourage more people to use biometric mobile payments for larger amounts.
For many customers, the most practical feature to look at right now is not a future higher limit – it is the ability to set their own lower one.
If fraud or impulse overspending concerns you, the personal-limit option is important. Setting contactless spending at, for example, £30 or £50, or disabling it completely, gives you more control than a nationwide rule could provide.
Balancing speed and security
Contactless succeeds because it is quick: no PIN, no signature and no delay in the queue. The compromise is that anyone in possession of your card can spend up to its limit before the bank identifies unusual activity or the card is blocked.
Banks bear much of this exposure themselves. They already absorb substantial fraud losses and are likely to be cautious about changes that could make stolen cards easier for criminals to exploit. This is why industry representatives expect gradual development rather than an instant move to very high limits.
For most people, the main threat is not a highly sophisticated criminal operation. It is misplacing a wallet on a Friday night and only realising the following morning. In that case, your contactless limit, the cumulative “PIN needed” threshold and how rapidly you can freeze your card in the app can all affect the scale of the loss.
Practical scenarios and points to consider
If limits increase in future
Suppose your bank eventually makes a £200 contactless limit the default. This could be useful for a weekly grocery shop or for buying petrol and coffee in one transaction. However, it would also allow a stolen card to build up greater losses faster before you take action.
In that circumstance, you may wish to:
- reduce your personal limit to £100 or below
- leave your mobile wallet active for larger purchases, using biometrics for those payments
- enable real-time transaction notifications so that every tap is visible immediately
How “cumulative” checks operate
Cumulative limits are less obvious, but they are equally significant. Your card provider monitors the amount you have spent contactlessly since your last chip-and-PIN payment. When you reach a particular number of taps or total-spend threshold, the terminal requires your PIN.
Under the new framework, firms can reconsider these thresholds. Some may tailor them more closely to your usual behaviour and risk profile. Others may make them less strict if they consider their fraud analytics sufficiently strong.
For customers, this could mean fewer unexpected PIN requests at the till - or, in some cases, more frequent verification where the bank identifies unusual activity.
Key terms to understand
Contactless limit: the highest amount that can be spent in one tap using a physical card without entering a PIN.
Cumulative contactless limit: a background safeguard that requires a PIN after multiple contactless payments or once a total spending level is reached.
Mobile wallet: a payment application, such as Apple Pay or Google Pay, which keeps card information on a phone or watch and generally uses biometrics or passcodes for every transaction.
The rule changes taking effect on Thursday do not require anyone to change how they pay, but they quietly redefine who decides how you tap, the amount you can tap for and how the risk is controlled. It may be more important to watch how your own bank uses this new authority - and which controls it gives you - than to focus on any headline figure in a regulator’s rulebook.
Comments
No comments yet. Be the first to comment!
Leave a Comment