
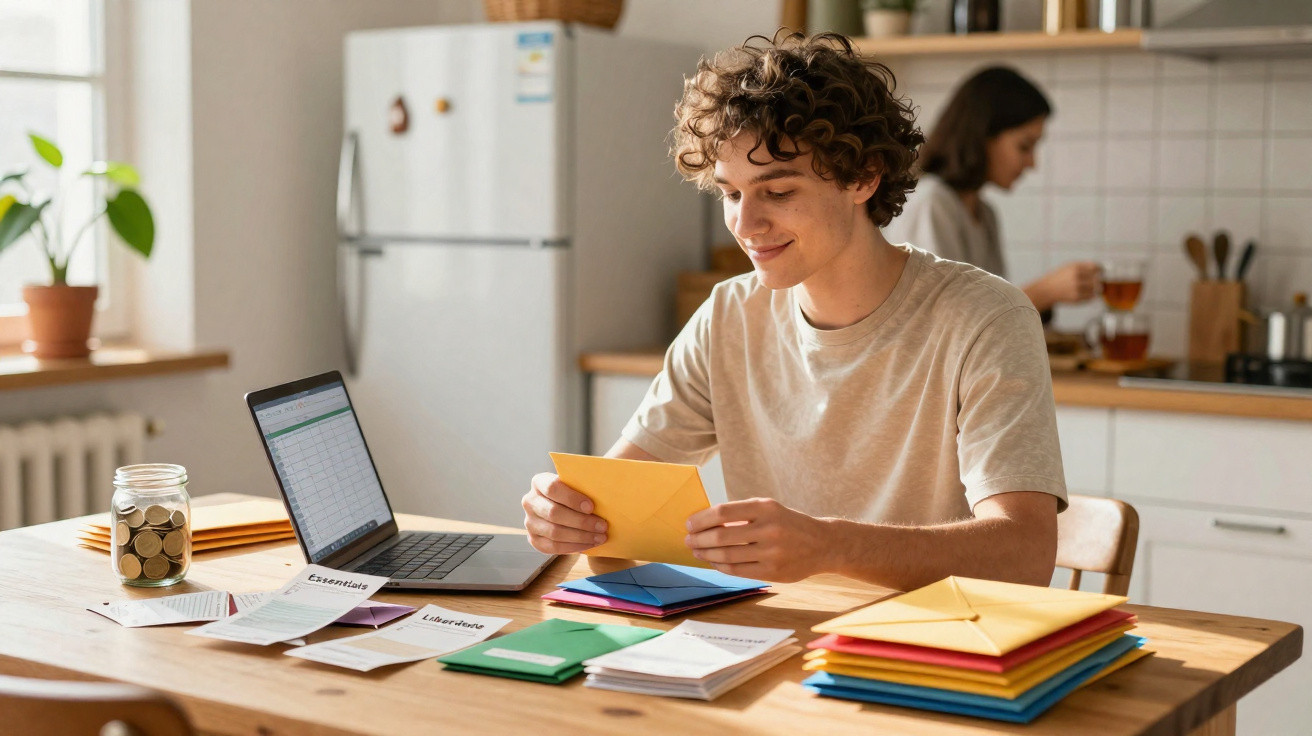
That message appears on a Sunday afternoon, wedged between a half-folded basket of washing and a cup of coffee gone cold: “Your account balance is below…” Before you have even read the rest, your stomach drops. You swipe it away, grimace and promise yourself that you will sort it out “next month, when things calm down.” Yet things never quite settle. Your pay still arrives. Your bills are still paid. Even so, money remains a faint alarm at the back of your mind: never entirely quiet, but never quite urgent enough to force action.
You are not exactly broke. You are simply… never at ease.
Something is absent from the system, and your mind senses it before you consciously do.
Why money stress lingers even when income is coming in
Look around an open-plan office or a packed Underground carriage and you can spot it: people glancing at their banking apps, slight frowns and brief sighs. On paper, many are financially “doing okay”. They earn reasonable salaries, cover the rent and order a takeaway without much thought. Still, money feels like a weight in their chest.
It is not simply about the amount arriving in. It is about the disorder beneath it.
Consider Maya: 34, a project manager with a good job and no children. A look through her bank statements reveals a recognisable pattern: rent, streaming subscriptions, takeaways, a gym membership she rarely uses, and several late-night Amazon impulse purchases at 11:47 p.m. There is normally some money remaining at month end. But she could not tell you how much without looking it up.
When her car unexpectedly breaks down, her stress goes through the roof. She has savings “somewhere”, but no dedicated emergency pot, written plan or regular routine. Managing money turns into a guessing game that she repeatedly loses.
Our brains dislike this sort of vagueness. If money sits in one large mental drawer marked “hope this works out”, your nervous system stays on guard. It keeps asking: Can I afford this? Have I overlooked something? Am I falling behind everyone else? Without a basic framework-separate pots, rules, dates and priorities-your mind must carry out the work that the system is not doing. That is draining. Financial stress persists less because of poverty and more because of uncertainty. Uncertainty, in turn, flourishes when there is no structure.
Financial stress and the mental cost of no structure
Many of us manage our finances through what experts describe as “open loops”. They include subscriptions we planned to cancel, old accounts we never shut down and cards that renew on arbitrary dates each month. Every minor unfinished task is another tab left open in your mind. You may not actively think about them, but your brain continues to manage them in the background.
A structured approach is, essentially, a way to close those tabs and reclaim mental capacity.
Picture two people with identical incomes and bills. Sam uses one current account for everything. His pay goes in, rent comes out, he spends what he spends, and anything left simply… drifts. There are no dates, labels or plan. Layla divides her money as soon as it arrives: fixed bills go into one account, everyday spending into another, and automatic transfers go to savings on the 2nd of every month.
By the end of the month, Sam feels baffled and guilty. Layla feels… slightly bored. And bored is preferable. Bored means her system is carrying the worry rather than she is.
Without a structure, every purchase becomes a small committee meeting in your head. Can I afford this meal out? Will I regret booking this trip? Do I really need the item in my basket? You are always bargaining with yourself because there is no set of rules to consult. Eventually, those internal negotiations become ongoing financial anxiety. Money stress becomes your default background noise, not because disaster is happening, but because anything could be happening and you wouldn’t notice until it’s too late. Structure is not about flawless spreadsheets. It tells your brain: “You can stand down. We have a process.”
How small money systems begin to reduce the noise
The simplest way to ease money stress is not necessarily to earn more; it is to decide what each pound, euro or dollar is for before spending it. This does not require a 40-page budget. It calls for a straightforward, flexible structure. Assign your money roles: one account supports future you, another pays for everyday life, and another handles the “oh no” moments. Then automate as much of it as possible.
As soon as you separate money according to its purpose, the haze starts to lift.
Many people attempt to solve money stress through determination alone. They pledge to “track every expense”, install three apps, colour-code their categories and leap from zero to chief financial officer overnight. After two weeks, they are exhausted, behind on entering receipts and convinced they have failed. In truth, nobody consistently does all of that every single day.
A better option is to introduce one manageable, lasting system at a time. Set a repeating calendar reminder to review your accounts on the same day each week. Arrange a regular monthly “money date” to transfer funds between accounts. Establish one unchanging rule for debt repayments. Gentle is more effective than heroic.
“Structure is not about restriction. It’s about relief,” a financial therapist told me. “People think systems will make them feel trapped. Most of the time, they finally feel safe.”
- Set up two or three separate accounts with distinct purposes: bills, everyday spending and savings.
- Choose one set day after payday to distribute money into each account.
- Automate those transfers, so they happen whether or not you feel motivated.
- Book a 20-minute monthly “money check-in” rather than scrutinising your finances every day.
- Include a guilt-free amount of “fun money” so the system feels human rather than punitive.
Living with money rather than against it
Once people add even a little structure, there is often a subtle change. Financial surprises do not disappear. The car can still fail, the dentist can still ring and prices can still increase. What changes is that these events land within a system instead of a void. You know where the emergency money is held, which bill can be delayed and which goal can be put on hold.
Stress does not disappear. It simply no longer feels like chaos.
We have all experienced that moment of being scared to open a banking app because we genuinely have no idea what will be there. A structured system will not remove that fear overnight, but it does make it smaller. It changes money from an unclear threat into a group of figures you can actually work with. You go from reacting to money to relating to it. That is a quiet form of adult power.
Often, that is enough to ease the tightness in your chest, even when your income has not increased by a single penny.
Behind the spreadsheets, apps and clever tricks lies a simple truth: most people don’t need more discipline, they need fewer decisions. When your financial life is guided by routine rather than improvisation, your brain gradually believes that one forgotten bill will not bring disaster. Money may still be tight. The future may still be uncertain. But there is solid ground beneath your feet, even if the ceiling is not yet as high as you would like.
That is often when the more important question can finally emerge: what do you want your money to do for you once it stops frightening you?
| Key point | Detail | Value for the reader |
|---|---|---|
| Structure reduces uncertainty | Clear accounts, dates and rules take the place of guesswork | Reduces persistent financial anxiety and mental load |
| Small systems beat big intentions | Straightforward, repeatable habits work better than “perfect budgeting” | Makes managing money feel achievable and sustainable |
| Purpose-based money pots | Giving every unit of money a role (bills, savings, fun) | Provides control, clarity and room for guilt-free spending |
FAQ:
- Question 1 Why do I feel stressed about money even when I’m not in debt? Your brain responds to uncertainty, not only to danger. When you do not know what is coming in, going out or what your money is intended for, your nervous system sees this as a risk, even if the figures are not disastrous.
- Question 2 Do I really need multiple bank accounts to feel more in control? Not necessarily, but dividing money into at least two or three pots-bills, everyday spending and savings-is among the quickest ways to reduce uncertainty and avoid accidental overspending.
- Question 3 What if my income is irregular or freelance? Structure remains useful. Build your system around a “minimum safe income”, then treat anything above it as a separate bonus and move it into savings or towards future months to smooth out quieter periods.
- Question 4 How often should I check my finances? For most people, a weekly review lasting 10–20 minutes, plus a more thorough monthly check-in, is sufficient. Checking every day can increase anxiety without leading to better decisions.
- Question 5 What’s one first step if I feel totally overwhelmed? Choose a “money day” this week, spend 20 minutes listing every fixed monthly cost, and start there. That one step gives you a baseline and makes each decision that follows easier.
Comments
No comments yet. Be the first to comment!
Leave a Comment