
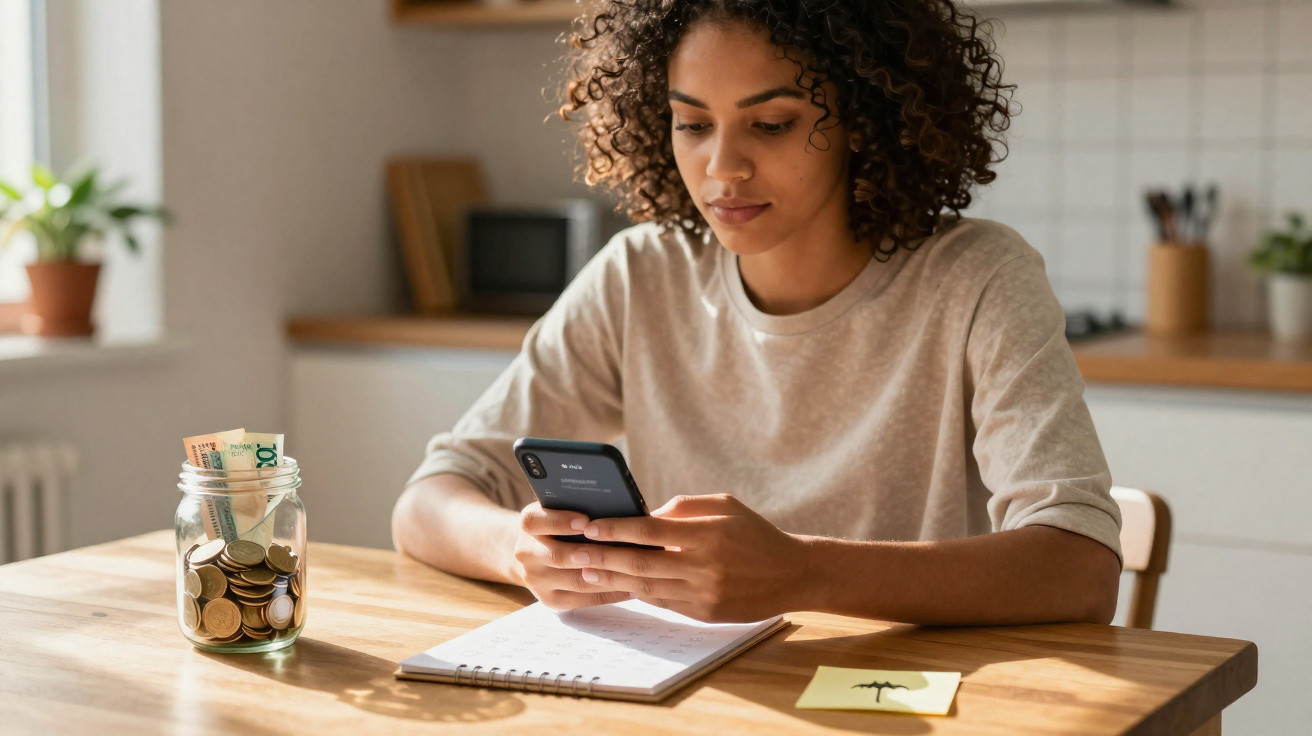
She froze. Council tax adjustment: £286. It was neither enormous nor insignificant, yet it was enough to make her stomach sink. Her rent was due the following week, the car needed replacement tyres, and payday felt a long way off. She checked her banking app, looked at the figures and did what most of us would do: sighed, shifted cash between accounts and told herself she would “get organised” next month.
That evening, on the sofa with a budget takeaway and a streaming programme paused, she spotted a small option in her banking app: “Automatic transfer from each paycheck”. Within five minutes, her future emergencies had a discreet new protector. The following morning, everything looked the same: same job, same bills and same life.
But the next crisis would now feel different.
Why your emergency fund never gets started
People usually do not struggle to save because they are careless. They struggle because life always feels a little urgent. There is always a birthday, a rail ticket, a dripping tap or a half-price jacket calling your name. Money that appears to be “spare” on paper does not remain spare for long when it is sitting in your current account, shining from the screen.
We say we will transfer money to savings “at the end of the month, if there’s anything left”. Usually, there is not. By that point, the overtime you expected has not materialised, one large food shop has become three smaller ones, and the energy bill has edged upwards. The emergency fund remains a concept rather than a balance. Ideas do not cover vets’ bills or boiler repairs.
It may look straightforward in a spreadsheet, but real life is complicated and human. That is why the answer is not greater discipline. It is fewer decisions to make.
Consider the figures. UK estimates indicate that roughly one third of adults have less than £1,000 in savings, and many have considerably less. A damaged phone, an urgent dentist appointment or a last-minute train journey to visit an ill parent can leave a credit card or overdraft as the only available “plan”.
Still, when you speak to people individually, almost everyone says something similar: “I’ve been meaning to build an emergency fund.” Intending to. Planning to. Not quite doing it. Nobody is to blame; the system simply encourages spending before you safeguard yourself.
Emma’s first automated transfer was £20. It was tiny, almost laughably so. Yet after six months, £240 was sitting there quietly. There was no dramatic gesture or viral productivity trick, only a background system doing what she had never quite got round to doing herself. When her boiler failed, that unexciting little balance suddenly seemed heroic.
The understated reality is that your brain can do many things brilliantly, but it is not designed to run a savings plan 24/7. Work, children, notifications and constant low-level pressure drain willpower on smaller problems long before it can be directed towards money.
So the usual advice - “each month, move some money into savings” - often runs into a problem. By the time you mean to do it, another expense has swallowed the money. Perhaps you are feeling low, or exhausted and ordering a takeaway instead. Let’s be honest: nobody really does that every day.
Automation avoids that fragile decision-making moment. There is no internal argument, no weighing up five competing priorities and no persuading yourself not to bother. The transfer simply happens. That is the genuine strength of an automated emergency fund: it continues on the days you would not manage it yourself.
Building an automated emergency fund in the background
Begin with an amount that feels almost embarrassingly small. Choose a figure you would spend on snacks without a second thought - £5, £10 or £15 from each paycheck. Go into your banking app or payroll portal and arrange an automatic transfer for the day after payday, rather than the same day. That small delay helps your mind accept the lower balance as “normal”.
Move the money into a separate savings account, ideally with another bank or at least somewhere that does not appear on your main dashboard. Give it an unmistakable name: “Emergency Fund – Do Not Touch”. Whenever your salary arrives, a small portion will quietly move into safety before you have time to notice it.
Once it is in place, stop aiming for perfection. Your role is no longer to manage every detail; it is simply not to cancel it.
The most common error is setting the target too high at the outset. People hear that they “should” have three to six months’ worth of expenses saved, feel hopelessly behind and attempt to reach that point in one ambitious jump. They arrange a £300 monthly transfer, then abandon it after two paychecks because it is too painful.
Treat it as you would taking up running. You would not go from the sofa to a marathon in a night. First you walk to the end of the road, then a little further. Money works the same way. Start with a sum you hardly notice. When you receive a modest pay rise or an outgoing ends, increase it by £5 or £10. Keep it quiet, unexciting and manageable.
During a difficult month, you may want to pause the transfer “just this once”. That is the risky point. Speak to yourself as you would a friend: compassionately, but with resolve. If you genuinely need to, lower the amount rather than turning it off altogether. At the beginning, maintaining the habit matters more than the total.
“The real flex isn’t buying something expensive on impulse. It’s knowing that when life throws a punch, you can take the hit without going under.”
Writing down a few straightforward rules can help you stay on course. There is no need for anything elaborate, just a brief guide to check when temptation strikes. Keep it in your notes app, on the fridge or beside your laptop. On a hard day, it can remind you what your calmer self decided beforehand.
Your guide might look like this:
- Target: £500 as an initial emergency fund milestone, then build towards one month of basic expenses.
- Transfer: An automatic transfer of £15 from each weekly paycheck (or £60 per month).
- Access: Use it only for genuine emergencies - job loss, urgent car or home repairs, medical or pet bills.
- Adjustments: Add £5 to transfers whenever your income increases or a regular bill ends.
- Temptation rule: Wait 24 hours before using the fund for anything that is not urgent.
Let your future self feel grateful, not desperate
As your emergency fund grows, a subtle change happens. You will still face workplace stress, family problems, broken boilers and unreliable tyres. Life does not become magically easier. But one layer of panic disappears. You deal with the issue, your savings balance takes a knock, and the automation quietly starts rebuilding it.
One day, you will check the balance and understand what security feels like in real terms. It is not a lottery win or an imagined moment of “financial freedom”. It is the quiet certainty that, if your manager called you into a meeting or the dog limped across the kitchen, you would have options.
That is the strange thing about automating small transfers. Initially, it seems insignificant: a fiver here, a tenner there, just background noise. Then, on an ordinary Tuesday several months later, you need it. You open the banking app, see that balance waiting for you and may genuinely breathe out loud.
We all know somebody who is one difficult week away from disorder. Sometimes that person is us. You cannot control the economy, your landlord or the cost of petrol. You can control one simple instruction to your bank, quietly moving a little of today’s comfort towards protecting your future self.
The issue is not whether life will bring an emergency. It is which version of you will meet it: the one scrambling for available credit on a card, or the one who created a quiet, unglamorous, automated safety net months earlier.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Automate every paycheck | Set up a fixed transfer for the day after each salary arrives in your account | Removes the need for willpower and excuses, making saving regular |
| Start small, then increase gradually | Begin with an amount you barely notice and raise it when your income changes | Keeps the habit manageable, so you do not stop after a few months |
| Keep the fund separate and clearly labelled | Use another account called “Emergency Fund – Do Not Touch” | Lowers temptation and makes your safety net visibly ring-fenced |
FAQ
- How much should I aim for in my emergency fund? For an initial goal, target £500–£1,000. Then work towards one month of essential expenses, followed by three months if your work or income is less secure.
- What qualifies as a genuine emergency? Job loss, urgent car or home repairs, medical or dental costs, vets’ bills and last-minute travel due to serious family circumstances. It does not include holidays, sales or birthday gifts.
- How often should I review my automatic transfers? Check them every 3–6 months, or whenever your income or major bills change. Use those opportunities to increase your transfer slightly.
- Where should I keep my emergency fund? Keep it in an easy-access savings account, preferably one paying some interest and positioned slightly “out of sight” from your everyday spending account.
- What if I need to use it for something that is borderline? Apply a 24-hour rule. Wait one day before taking money from the fund. If it still seems genuinely urgent the next day, use it - that is what it is for - and allow the automation to rebuild it afterwards.
Comments
No comments yet. Be the first to comment!
Leave a Comment