
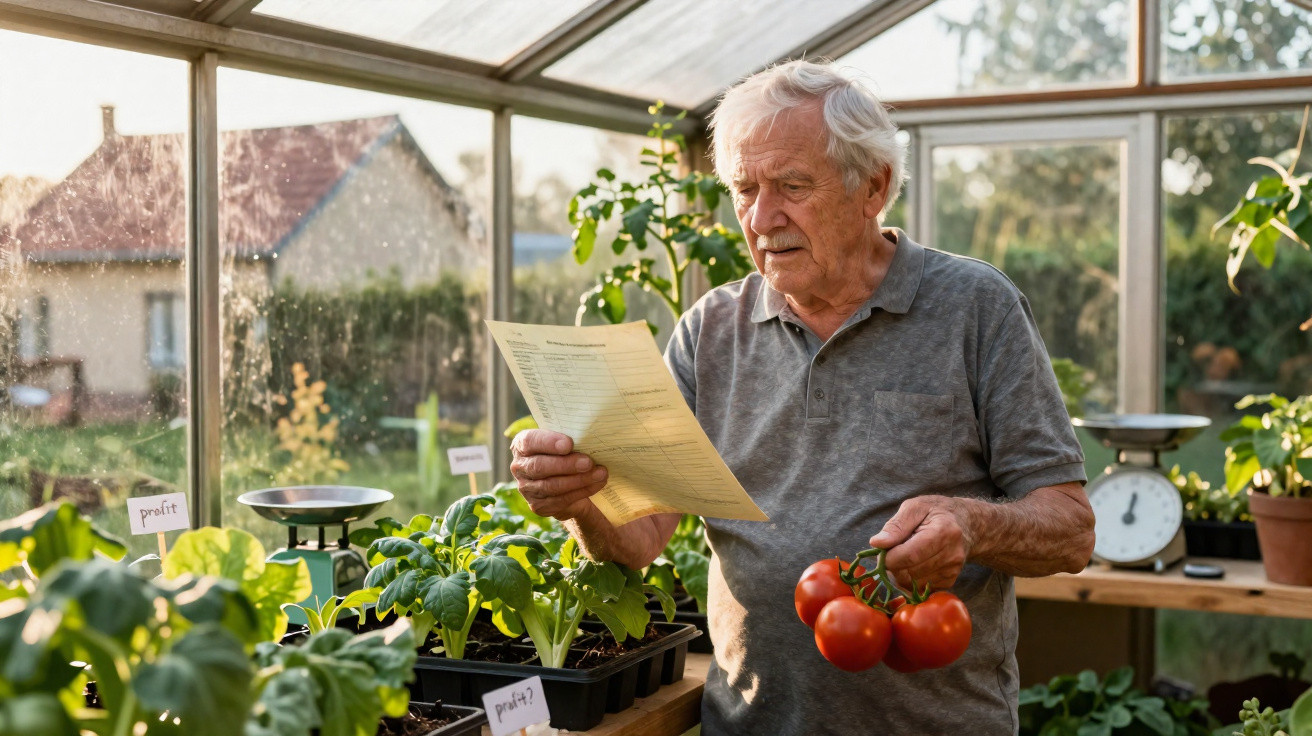
At 7:15 on a Tuesday morning, the light inside Margot’s modest suburban greenhouse has an almost sacred quality. Tomatoes wind up their strings, basil scents the damp air, and an old chipped radio murmurs familiar songs. She makes her way carefully between the pots as her arthritic knees complain, yet her hands still recognise every plant instinctively. The glass structure at the end of her garden is not an asset to her. It is a sanctuary.
This year, however, that delicate calm has been disturbed.
A letter from the tax office sits folded beside an almost untouched cup of coffee on her kitchen table. New regulations. New declarations. A new tax on “private garden greenhouses”. Margot reads the wording again and again, unable to understand how her dozen tomato plants have been placed in the same category as small professional growers.
The argument is already reaching far beyond her garden fence.
A new tax arrives in the vegetable patch
The new tax on private garden greenhouses has landed like a storm breaking on an otherwise sunny day. In theory, its purpose seems straightforward: separate hobby gardeners from people quietly operating a business from their back garden. In real gardens, and in real lives, the distinction is far less tidy.
Local councils are now recording greenhouses that previously attracted little attention. Pensioners who once discussed compost and ways to deal with slugs are now talking about square metres, limits and official paperwork. Some are shocked to find that an ordinary glass structure is being regarded as taxable equipment.
Behind the official language, one practical worry is taking hold: could producing a few additional cucumbers become a financial liability?
Consider Bernard, a 74-year-old retired mechanic who has grown vegetables “for the joy of it” for three decades. His greenhouse has been repaired with mismatched panes; some are slightly clouded, while others are secured with tape. During summer, he gives neighbours crates of tomatoes and, yes, sells a few at the Sunday market to cover the cost of seeds.
Under the new tax scale, Bernard’s 18 m² greenhouse exceeds the stated threshold. A tax officer tells him by telephone that repeated sales, however small, may be viewed as semi-professional activity. Bernard ends the call in disbelief.
What used to be a social exchange - a few euros, a smile, a handful of coins - now appears to resemble undeclared turnover.
Administrations favour firm boundaries, but everyday life seldom fits them. The new tax attempts to separate the “pleasure greenhouse” from the “profit greenhouse”. Square metres, turnover caps and sales frequency are all converted into numbers.
In many villages, though, one greenhouse feeds a household, supports a neighbour and occasionally supplies the local grocer. Such overlapping purposes do not sit comfortably in official classifications. On paper, the rule looks rational; in gardens, it feels clumsy.
The result is a split few people had sought: “real” pensioner-gardeners on one side, and “disguised micro-farmers” thought to be avoiding tax on the other.
Private garden greenhouses: declaration, adaptation and quiet resistance
For anyone facing these new rules, the first step is unglamorous but clear: measure, list and assess. What is the actual size of your greenhouse? Do you sell any produce, even from time to time? How frequently do you sell, and who buys it? A notebook and tape measure are enough to carry out this small personal review on a Sunday afternoon.
People making regular sales - through small baskets, market pitches or repeated sales to neighbours - may find themselves close to the thresholds without noticing. Some tax services now ask pensioners to declare how their greenhouse is used on a simplified form. It is laborious, but it creates a written record that may prevent confusion or penalties later.
Oddly, the smaller the earnings, the more burdensome the administration can feel.
The most frequent error is dismissing the matter with: “I sell so little, they’ll never come after me.” Many well-intentioned people regret that assumption when a compliance letter arrives. Another danger lies in trusting hearsay: “My neighbour told me that under 20 m², nothing counts.” Rules rarely correspond exactly with what is said in chats over the garden hedge.
Speaking to a gardening association, a local council officer or a tax adviser at a drop-in session can often resolve matters quickly. And no, you are not “bothering them”; it is quite literally their role. These letters can cause a genuine emotional jolt, particularly for people surviving on a limited pension. Greater certainty can ease that knot in the stomach.
Let’s be honest: nobody really reads the full tax bulletin every year.
“Yesterday, I was just the old lady with strawberries for the kids,” sighs Colette, 79, who sells jam jars at the village fête. “Today, I feel like they see me as a small tax fraudster with my greenhouse. I’m not cheating anyone. I’m just stretching my pension and avoiding waste.”
Her remarks resonate at kitchen tables across many communities. Several practical options are emerging for dealing with this new situation:
- Keep sales limited or clearly defined: make them occasional, symbolic, or declare them as a micro-activity if they become regular.
- Keep evidence of your activity: a basic notebook recording harvests and sales may demonstrate that you are not operating a concealed business.
- Request written guidance from the local tax office rather than depending on “everyone knows that…”.
- Work collectively through gardening clubs or associations to obtain shared answers and influence future revisions.
- Consider sharing or bartering instead of selling when the purpose is genuinely neighbourly support.
When a greenhouse represents more than money
Beyond the figures, a quiet cultural conflict is unfolding at the bottom of gardens. For many pensioners, the greenhouse is the final space in which they can feel genuinely useful, inventive and free of pressure from household bills. Seeing that place suddenly defined through tax classifications can feel intrusive.
At the same time, some people have truly turned their greenhouse into a second job or an additional source of income. They invest money, calculate output and negotiate prices. They maintain that taxation is reasonable when it supports public services, provided the limits are realistic and the regulations understandable. Suspicion is rapidly increasing between these two groups: “real” amateurs and supposed profiteers.
Still, on market mornings, they stand alongside each other and compare how this year’s tomatoes have performed.
Some pensioners have already begun to adjust. A number are dismantling or reducing their greenhouses to remain below a particular limit. Others have stopped selling altogether and switched to barter: a crate of tomatoes for bicycle repairs, or a bunch of dahlias for help with a computer. It is a quiet informal economy beyond digital systems and official classifications.
On social media and local forums, outraged messages sit alongside practical suggestions. Several gardening associations have started collecting accounts in support of changes: higher thresholds for pensioners, exemptions for very small and clearly non-professional structures, and easier declarations. The same message can be heard between the lines: “We’re not against contributing, but we want to be treated fairly.”
There is a generational aspect to the issue too. Adult children are discovering that parents they believed merely “just pottered around with plants” were supplementing modest pensions through a handful of discreet sales. Some respond with concern, others with anger, and some with quiet pride in that ingenuity.
Public discussion is likely to intensify the contrast between pleasure and profit. Yet beneath the greenhouse glass, reality often falls between those labels. A greenhouse can cut supermarket spending, provide food for grandchildren and generate a little cash at the same time. Treating it as having only one purpose - taxable or otherwise - overlooks much of the picture.
The question now hanging over gardens is both simple and unsettling: how far should the State reach into our vegetable patches?
| Key point | Detail | Value for the reader |
|---|---|---|
| New greenhouse tax logic | Separates “pleasure” use from repeated sales that resemble micro-farming | Helps you understand where your own activity falls on the spectrum |
| Risk zones for pensioners | Area thresholds, sales frequency and missing records create grey areas | Enables you to prepare for checks and lessen financial or legal stress |
| Concrete defensive strategies | Measuring, keeping simple records, collective action, and moving from sales to sharing or bartering | Provides practical ways to retain your greenhouse without losing sleep |
FAQ:
Do all private greenhouses get taxed now?
No. The new framework targets structures and uses that look like regular production for sale. A small greenhouse used only for family consumption is treated very differently from a larger one that feeds a weekly stall.Is giving vegetables to neighbours considered taxable?
No, gifts and informal sharing without money involved are not taxable income. The issue starts when there are repeated, organized sales, even for small amounts.I sell a few crates per year at the local market. Is that a problem?
It depends on how frequent and how structured those sales are. Occasional, symbolic participation is less sensitive than a predictable, recurring activity. Getting written advice from the tax office on your case is safer than guessing.Can dismantling or reducing my greenhouse change anything?
Yes. Some rules use surface area as one of the criteria. Reducing size, or clearly separating a “test tunnel” from your main greenhouse, can shift how your setup is classified.How can pensioners defend their situation collectively?
By joining local garden clubs, retirees’ associations or small producers’ groups. They can gather real-life cases, request meetings with local officials, and argue for thresholds or exemptions adapted to non-professional, low-income gardeners.
Comments
No comments yet. Be the first to comment!
Leave a Comment